The scope of application is sorted out according to the current rules of the regulatory agency and company registration authority in the place where the fund is registered., Process information, Cost budget and subsequent maintenance.
Compliance focusEstablishing an offshore fund, Cayman CIMA Financial License, Cayman SPC Fund, Hong Kong LPF Fund, Wealth inheritance structure, International financial licenses and offshore supervision
Previous organisation typesInternational family office; Offshore trust structure service provider
Liang Yanting: 12 years of overseas company registration experience, Served in international family offices and offshore trust structure service providers, Good at setting up offshore funds, Cayman CIMA Financial License, Cayman SPC Fund, Hong Kong LPF Fund, Wealth inheritance structure and international financial licenses and offshore supervision. Particularly familiar with BVI, Cayman Requirements for Registered Agent and Beneficial Owner Registration, As well as Hong Kong’s regulations on local registered addresses and company secretaries, Able to synchronize notarization, certification and annual review nodes during the establishment phase, Avoid subsequent returns.
1. Establishing an offshore fund: Processing background and scope of application
The establishment of offshore funds is not simply the registration of an offshore company.. Fund carrier, investment manager, Raise or issue, Distribution, Custody and investor anti-money laundering may be affected by where the fund is registered., Regulations governing the place of management and fundraising; Do you need to register?, Permission or application of private placement exemption must be determined layer by layer.
The project should first determine whether it will be an open or closed structure, Investment Strategies and Asset Classes, target investors, Minimum subscription, Redemption and lock-in, Valuation, lever, Fees and Allocations, Compare companies again, Forms such as limited partnerships or unit trusts. Cayman Private Equity, Mutual funds and funds from other jurisdictions cannot be treated uniformly as “offshore funds”.
Important tips: Fund establishment involves securities issuance, investment management, Tax and Investor Territory Rules, should be assessed separately.
2. Core processing information
Competent or accepting agency
Regulatory agency and company registration authority of the place where the fund is registered
The specific acceptance unit and authority shall be subject to the latest public information of the regulatory agency and company registration authority of the fund registration place..
Service type
Offshore fund structure establishment and ongoing compliance support
Fund establishment involves securities issuance, investment management, Tax and Investor Territory Rules, should be assessed separately.
Key checks
Data consistency and business authenticity
The content is organized based on the disclosure rules of regulatory agencies and adjacent regulatory systems..
3. Service scope and delivery boundaries
Scope note
The following content is used to delineate the scope of projects for establishing offshore funds; The actual business and official determination remain controlling.
Fund type and registration location selection
Organize information around fund type and registration location selection, Gaps and follow-up implementation matters.
administrator, Configuration of administrative managers and service providers
around managers, Administrators and service providers configure and organize information, Gaps and follow-up implementation matters.
Raising documents, AML and continuing filings
around fundraising documents, AML and continuous filing data collection, Gaps and follow-up implementation matters.
4. subject condition, Personnel and application information
Check before handling
Regulatory agencies and company registration authorities at the place where the fund is registered usually obtain information from the entity., personnel, business substance and risk controls; The required depth of documentation varies by project.
Prepare company registration documents, director, shareholder, Ultimate beneficial owner and authorized contact information.
Description of business and purpose
Explain the purpose of applying for offshore fund structure establishment and ongoing compliance support, customer or counterparty, regions, Estimated scale and actual capital flow.
supporting documents
Provide address as required by the handling agency, Source of funds, contract, Tax or business certification.
Risks and follow-up arrangements
Identify sanctions, Anti-money laundering, tax, Declaration and subsequent maintenance requirements, and designate an internal person in charge.
Capital and financial resources
There is no uniform amount that applies to all projects; Matters should be handled according to actual conditions, Place of registration, License category, Calculation of business scale and current rules of the competent authority.
Key persons and governance
Directors should be confirmed first, company secretary, Compliance, Legal roles such as finance and local contacts, Then allocate personnel who are authorized to perform duties according to the actual business.
Premises and local substance
Registered address, actual office, Bank correspondence address and license required premises are not the same concept. lease, use, Personnel presence and record-keeping requirements must be checked by jurisdiction and specific service..
5. State fees and project budget
The budget should differentiate between statutory expenses, Capital or margin, corporate and premises costs, staffing and professional fees. Do not quote a fixed total cost or guarantee an approval timeframe without an official basis.
Budget item
Basis of calculation
Checkpoints
Government or authority fees
According to the selected registration place, Fund type and applicable entity registration, Fund registration or licensing procedures, Check with the competent authority’s current fee schedule; Company establishment fees and fund supervision fees are calculated separately.
Only quote the current fee schedule of the competent authority; Third-party service fees must not be presented as government fees.
capital, security deposits and insurance
There is no uniform amount that applies to all projects; Matters should be handled according to actual conditions, Place of registration, License category, Calculation of business scale and current rules of the competent authority.
Capital is not a service fee, and must not be met with temporary loans or funds of unexplained origin.
Company formation and statutory maintenance
Budget separately according to the place of registration, share capital, registered agent, secretary, Registered address, annual return and tax filings.
Company formation does not mean that a licence or bank account has been approved.
Office and personnel
Calculate according to the lease, deposit, floor area, use, local remuneration, visa and local-presence requirements..
Confirm the substantive requirement accepted by the regulator, before signing a lease or hiring staff..
Policies, systems and professional services
Calculate AML/KYC,, Sanctions Screening, transaction monitoring, network security, audit, legal advice, translation and notarisation according to business complexity..
Quotes should set out the scope, hypothesis, third-party costs and the number of response rounds.
6. Processing process and expected cycle
The timeline depends on business complexity,, Inquiries on data integrity and regulatory authorities in the place where the fund is registered and the company registration authority or acceptance agency, so a fixed approval time should not be promised..
Step 1: Clarify goals and scope of application
Confirm the goals for offshore fund structure establishment and ongoing compliance support, Handling area, Subject matter and intended use.
Step 2: Complete a gap assessment
Compare the requirements of the regulatory agency of the fund registration place, the company registration authority and the actual acceptance agency, Identify information and business substance gaps.
Step 3: Prepare and verify information
Organize the subject, personnel, business, Source of funds and supporting documents, Make sure the statements in each document are consistent.
Step 4: Submit and respond to inquiries
Submit information as required, Follow up on replacement parts, clarify, Face-to-face or remote verification.
Step 5:: Complete follow-up maintenance
Create a declaration after processing is completed, Renew, Information update and risk review calendar.
7. Post-completion maintenance and compliance
After establishment, investor due diligence must be completed in accordance with applicable regulations., Valuation, Net worth calculation, Financial statements and audits, Regulatory and tax reporting, FATCA/CRS, Board of Directors Minutes, Conflict of Interest Management and Notification of Material Changes. issuance documents, Investment limits and actual transactions must be consistent.
Cayman Department of International Tax Cooperation (DITC), Responsible for relevant tax information declaration matters (DITC official information).
8. 2023–2026 Rules Updates and Official Materials
When choosing a place of registration in 2026, you should also check the fund classification, Manager qualifications, beneficial owner, economic substance, Audit and reporting requirements; The historical "quick establishment" scheme cannot replace the regulatory analysis of the place of management and the place of fundraising..
Update note: regulatory scope, capital, personnel, cost, timelines and ongoing obligations may change, Before proceeding, follow the authority’s current rules, forms and case-specific determination.
9. Application preparation and document check
The following checklist is used for preparation and communication for establishing offshore funds, and maps the business description to verifiable evidence; the final submission items depend on the requirements of the applicable authority.
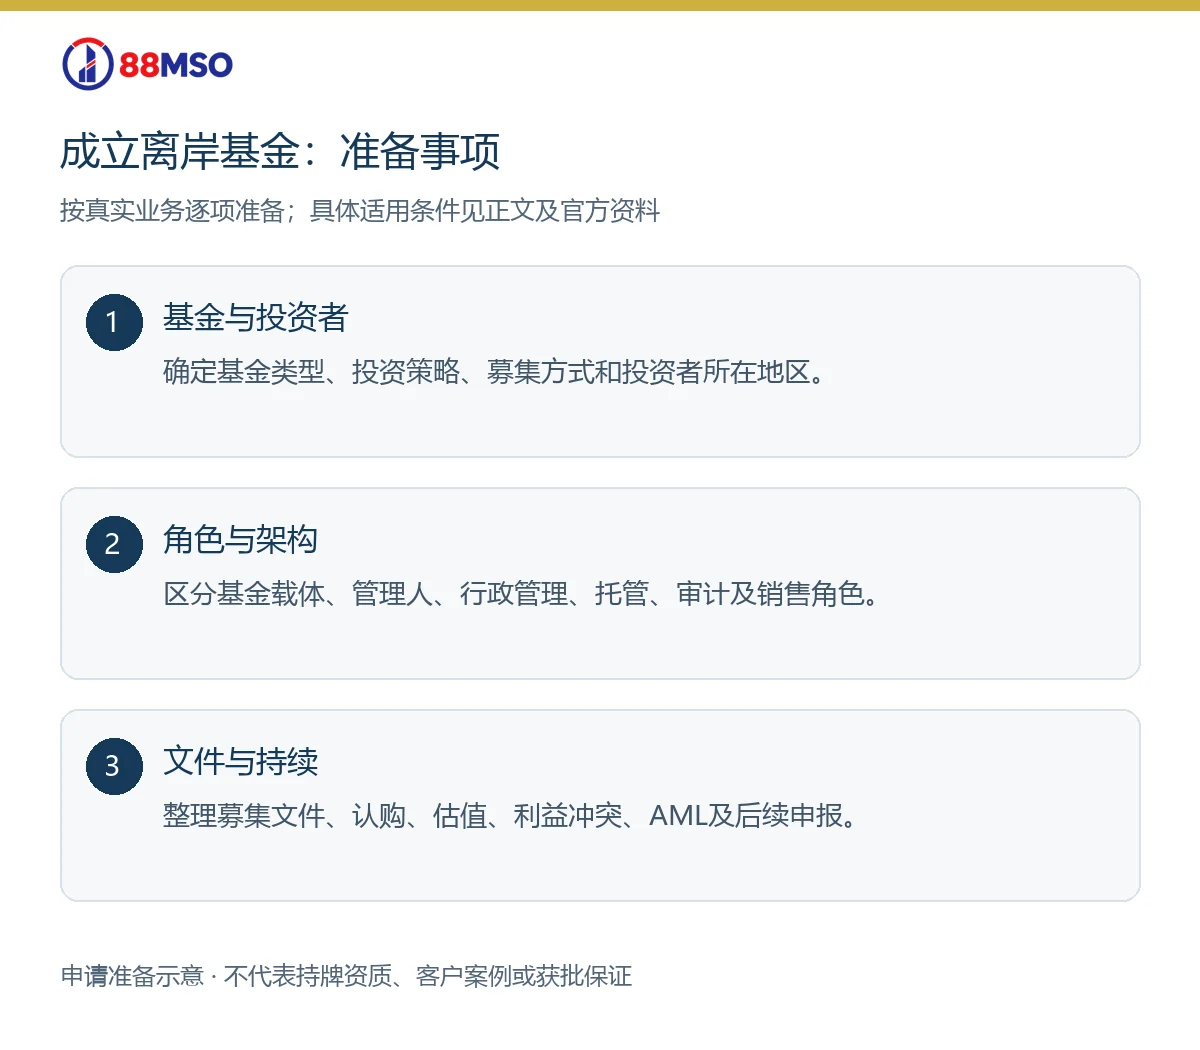
Key points for establishing offshore funds: Fund category, investor, Role architecture and persistence documentation.
Funds and Investors: Determine fund type, investment strategy, Fundraising method and investor location.
Roles and Structure: Distinguish fund carriers, administrator, Administration, hosting, Audit and sales roles.
Files and persistence: Organize fundraising documents, Subscription, Valuation, conflict of interest, AML and subsequent filings.
10. Frequently asked questions
The establishment of offshore funds is not simply the registration of an offshore company.. Fund carrier, investment manager, Raise or issue, Distribution, Custody and investor anti-money laundering may be affected by where the fund is registered., Regulations governing the place of management and fundraising; Do you need to register?, Permission or application of private placement exemption must be determined layer by layer. The project should first determine whether it will be an open or closed structure, Investment Strategies and Asset Classes, target investors, Minimum subscription, Redemption and lock-in, Valuation, lever, Fees and Allocations, Compare companies again, Forms such as limited partnerships or unit trusts. Cayman Private Equity, Mutual funds and funds from other jurisdictions cannot be treated uniformly as “offshore funds”.
Core information usually includes architecture diagrams, Investment and Cash Flow Description, Offering or Private Placement Memorandum, Subscription documents, Articles of Association or Partnership Agreement, Management and Administration Agreement, Valuation and Conflict of Interest Policy, AML/KYC system, risk disclosures, and managers, director, custodian, Certificate of Admission from Administrator and Auditor.
After establishment, investor due diligence must be completed in accordance with applicable regulations., Valuation, Net worth calculation, Financial statements and audits, Regulatory and tax reporting, FATCA/CRS, Board of Directors Minutes, Conflict of Interest Management and Notification of Material Changes. issuance documents, Investment limits and actual transactions must be consistent.
When choosing a place of registration in 2026, you should also check the fund classification, Manager qualifications, beneficial owner, economic substance, Audit and reporting requirements; The historical "quick establishment" scheme cannot replace the regulatory analysis of the place of management and the place of fundraising.. See the latest rulesCayman CIMA official regulatory information.
The regulatory qualifications of service providers should be assessed, Relevant asset experience, Systems and reporting capabilities, Area coverage, TOLL, Audit cooperation, Data security and exit arrangements. Choosing a well-known institution is not a substitute for fund management supervision, Key Responsibilities, Data and upgrade mechanisms should be clearly written in the agreement.
Other than statutory or regulatory capital, Also need budget legal documents, register, manage, audit, tax, hosting, Valuation, technology, Directors and ongoing filing costs, and consider operating periods when fundraising is lower than expected.. Any figures should be verified against the latest official rules and service provider quotes.
Cycles are affected by structural complexity, Service provider accepts, document negotiation, regulatory review, Bank and Brokerage Accounts and Investor Due Diligence Impact. Structural design should be, Documentation, Apply, Open an account, System access and first delivery phased plan, Should not commit to a single fixed date.
Valuation sources should be stated in offering documents and policies, frequency, unobservable price, cost sharing, Related party transactions, side pockets, Redemption suspension and error correction mechanism, and clarify who approves and independently reviews. Inconsistency between actual implementation and disclosure creates significant compliance and investor protection risks.
Escrow private keys are also typically evaluated, Trading Venue and Counterparty Risk, On-chain monitoring, market manipulation, Valuation, network security, sanctions, Liquidity and asset loss arrangements, and confirm the fund, The respective license scopes of managers and service providers.
Common matters include investor due diligence and ongoing monitoring, Financial Statements and Auditing, Regulatory and tax reporting, Valuation, Capital or net worth monitoring, investment restrictions, Board of Directors Minutes, Notifications of major events and updates to issuance documents. A compliance calendar should be established jointly maintained by the administrator and each service provider.
should beCayman CIMA official regulatory informationpublished there, application forms, guidance, fee schedules and notices as the current reference. 88MSO helps organise questions and materials, but does not represent a regulator, and cannot replace advice from local counsel, a tax adviser or the regulator on a particular case.
Government or competent authority fees should correspond to official fee schedules, payment notice or receipt.; capital, margin, Insurance, office, personnel, system, audit, law, translation and advisory services are separate budget items. Formal quotations should specify the currency, taxes, third party expenses, Applicable Assumptions and Exclusions.
The applicant should be confirmed first, statutory registered office, actual management location, and distinguish these from customer reception and recordkeeping locations, then budget for registration fees, agent or secretary, rent, deposit, furnish, communications, Insurance, visas and local staff. Leasing before defining the regulatory boundary, may create unrecoverable costs.
should beCayman CIMA official regulatory informationSubject to, And download or save the current version before submitting. 88MSO is used to organize application questions and documents, does not represent the competent authority, Nor does it use third-party web pages as a substitute for legal advice..
You cannot judge based on the establishment certificate alone. Recruitment method, investor, Fund supervision, Manager qualifications and sales area rules should be checked separately.
no. Fund carrier establishment, Fund registration or licensing, There are applicable requirements for manager and distributor qualifications respectively..
Not necessary. CIMA's Investment Fund Description lists common vehicles, including exempt companies, Separate Portfolio Company (SPC), Unit trusts and exempted limited partnerships. Legal carriers and fund supervision categories should be designed separately, Just because you have chosen a certain vehicle does not mean you have been approved by the fund.. SeeDescription of common legal vehicles for CIMA Cayman funds.
no. Conditions related to Registered Mutual Fund as stated by CIMA, The minimum total equity amount that potential investors can purchase is CI$80, 000(US$100, 000), or interests listed on a stock exchange recognized by CIMA. It cannot be directly interpreted for all funds, Capital requirements for managers or ordinary companies. SeeMinimum investment equity conditions for CIMA registered mutual funds.
CIMA's mutual fund definition involves interests that are redeemed or repurchased at the option of the investor, and pooling funds, Diversify investment risks and other factors. Open-ended and other fund arrangements should first be based on the redemption right, Law Applicable to Judgment of Investor Structure and Business Facts, You cannot choose a system based solely on the name "private placement" or "offshore". SeeCIMA Mutual Fund Definition and Regulatory Classification Explanation.
Guide to setting up offshore funds: Architecture choice, Setup process and fees | 88MSO88MSO was established around offshore funds, Focus on the place of registration of the fund, administrator, Investor qualifications, issuance documents, to help assess the relevant scope before applying, application documents and ongoing obligations.
 简体中文
 繁體中文
 English