简体中文
 繁體中文
 English

Singapore serves as an important hub for Chinese companies to go global,Registering a Singapore company and subsequent annual review are the focus of many customers。88MSO now provides unified answers on the company registration process and company annual review process。
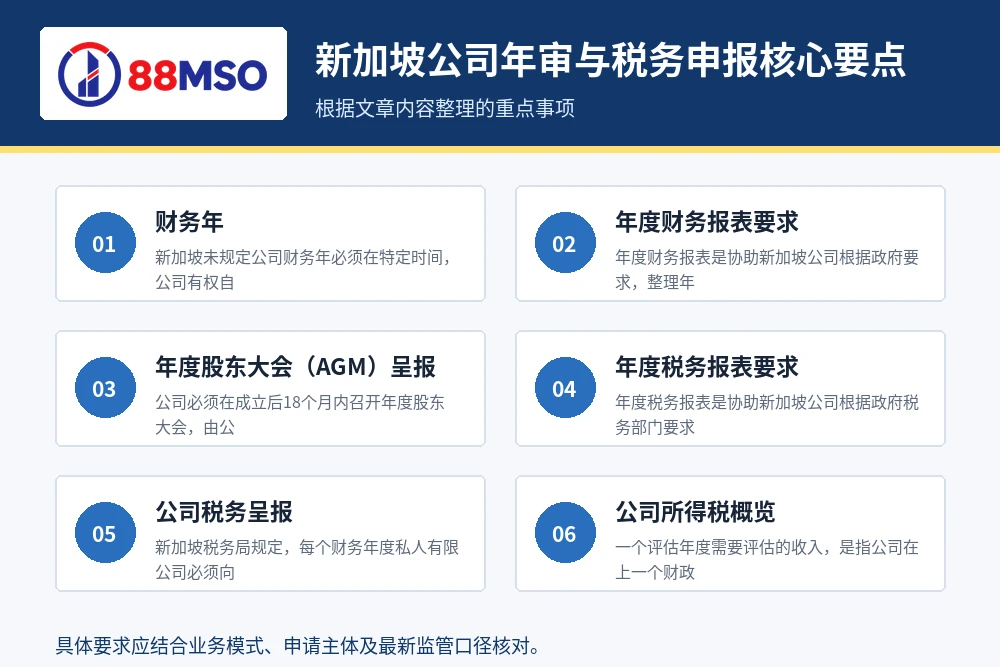
financial year
Singapore does not stipulate that a company’s financial year must be at a specific time,The company has the right to freely choose。Usually, the company determines the financial year time with the accounting company during the first annual review.,The first financial year shall not exceed 18 months,And it can be replaced later in the financial year.。
Annual Financial Statement Requirements
Annual financial statements are provided to assist Singapore companies in compliance with government requirements,Collate annual accounting accounts and prepare annual financial reports,The report includes accounting、Prepare directors' report、Director's Statement、Profit and loss statement、balance sheet、Cash flow statement and classification notes, etc.。
Annual General Meeting (AGM) Presentation
The company must hold an annual general meeting within 18 months of incorporation,Hosted by Company Secretary,All directors voted and signed various resolutions。
Annual tax statement requirements
Annual tax returns are provided to assist Singapore companies in complying with government tax department requirements,Prepare annual accounting accounts、Make annual tax estimates and complete tax return forms。
Corporate tax reporting
Singapore Inland Revenue Authority Regulations,Private limited companies must file corporate tax returns with the Inland Revenue Department every financial year。Corporation tax is calculated based on pre-tax profits for the financial year,rather than turnover。The Singapore private limited liability company tax rate is 17% (the first three years of the new company,The first 100,000 profits per year are tax-free)。
So far,This time, we have finished sharing about the Singapore company registration and annual review process.。If you have any questions,Welcome to contact 88MSO consultants。
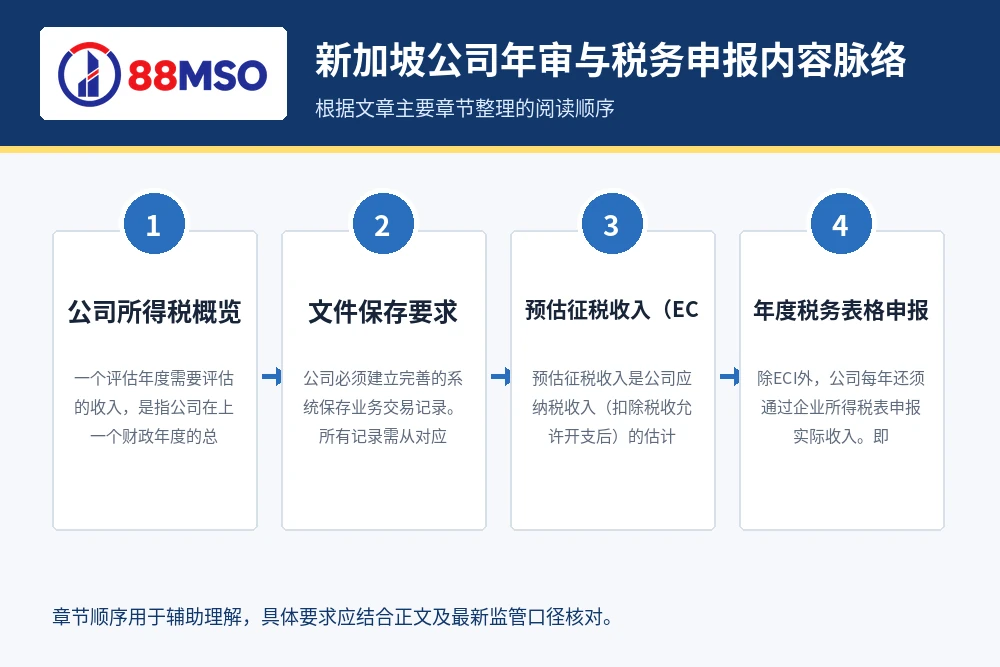
Corporate Income Tax Overview
Income to be assessed in a year of assessment,Refers to the company’s total revenue in the previous fiscal year。For example,If the company's fiscal year ends on December 31,Then the assessment year 2026 corresponds to the income from January 1, 2026 to December 31, 2026;If the financial year ends on March 31,Then the assessment year 2026 corresponds to the income between April 1, 2014 and March 31, 2026。The current corporate income tax rate for Singapore companies is 17%。
Important time points:Within three months after the end of the company’s financial year,Submit Estimated Taxable Income (ECI);Submit the corporate income tax form (Form C-S/C) before November 30 each year,If using electronic file format,Deadline is December 15th each year。
File preservation requirements
The company must establish a complete system to save business transaction records。All records must be retained for at least 5 years from the corresponding assessment year,and searchable by the Inland Revenue Authority of Singapore (IRAS)。For example,Financial records from January 1, 2026 to December 31, 2026 (fiscal year of assessment 2026),Should be kept until December 31, 2026。
Documents to be retained include:
- Source document,Such as invoice、Receipts and Vouchers
- Accounting records and schedules,Such as general ledger and sales list
- Bank statements and bank notes
- Other business transaction records
Estimated Taxable Income (ECI) Submission
Estimated taxable income is an estimate of a company's taxable income (after deducting tax allowable expenses)。This form must be submitted to the Inland Revenue Authority of Singapore within three months of the company’s financial year end。For example,If the company is established in 2026,Financial year end date is December 31, 2026,The ECI for the financial year ending on December 31, 2026 must be submitted to the tax bureau before March 31, 2026.。
1 year after the company was established,The Singapore Inland Revenue Authority will send a notice every year in the last month of the company’s financial year.,So that companies can fill out and submit the ECI。If no notification is received,Companies should submit ECI on their own within three months after the end of the financial year。
There is no need to submit an ECI in the following situations::
- Estimated taxable income does not exist (i.e. the company has no taxable income)
- Annual income does not exceed S$1 million
Tips:If the company fills out the ECI electronically and pays through GIRO,Enjoy 10 monthly installments。After submitting ECI,The tax office will send a notice of assessment by post (also available on myTax Portal)。Income tax must be paid within one month from the date of assessment notice。
Annual tax form filing:Form C-S / C
Except ECI,Companies must also declare actual income through corporate income tax forms each year。Even if the company loses money,The form still needs to be filled out。Corporate income tax forms are divided into Form C-S (simplified version) and Form C,You can fill in Form C-S if you meet the following conditions:
- Company established in Singapore,Annual income does not exceed S$1 million
- Companies are not required to report offsetting losses for the current year、Group relief、investment allowance、R&D tax relief、Sources of Foreign Tax Credits and Deductions
You can enjoy the following benefits by filling in your corporate income tax form electronically::Additional 15 days to fill in、Guidance every step of the way、Automatically correct some content to reduce errors、Save draft function、Estimate tax payable on the spot、Get instant confirmation after successful submission。
After submitting Form C-S/C,The Inland Revenue Authority of Singapore will send a tax notice,Explain whether the company needs to pay back taxes、Get a tax refund or no changes required。Any additional tax must be paid within one month from the date of the assessment notice。If you disagree with the tax position in the Notice of Assessment,Please notify the tax office by submitting a Notice of Objection within two months from the date the notice is displayed.,and explain the reasons。
electronic services:myTax Portal
myTax Portal is a secure one-stop tax service platform,Provide 24/7 service。Taxpayers can handle tax matters and check transaction status through this platform。Before visiting,You need to authorize yourself through the electronic service authorization system (E-Service Authorization)、Employee or third-party tax agent login。The required information includes:
- company tax number
- Corporate Electronic Services Access Code
- Personal tax ID number
- SingPass or Singapore Inland Revenue Authority PIN
Common tax deductions
For the company’s first three consecutive tax assessment years,Qualifying companies can enjoy the following reductions each year:
- The first S$100,000 of taxable income:Completely tax-free
- The next S$200,000 of taxable income:50% tax free
From the fourth year onwards,The reduction method is adjusted to:
- First S$10,000 of taxable income:75% tax deduction
- The next S$290,000 of taxable income:50% tax relief
This method is applicable to all companies that have not applied for the newly established company business tax exemption scheme。please note,It is illegal to abuse this policy to obtain tax relief through shell companies。
The above are the core points of corporate taxation in Singapore。For further information,Welcome to consult 88MSO consultants。
Related services:Singapore company registration
Dealing with both corporate and tax returns after the year-end
Singapore company annual review and tax declaration involve company declaration and tax declaration are not the same thing。Lock the fiscal year end date first,Then list the accounts separately、financial statements、Audit or exemption judgment、Annual Return and Tax Return Submission Points,It can avoid mistaking the completion of one declaration as the completion of all compliance.。
Bank statements should be filed on a daily basis on a monthly basis、Sales and purchasing documents、contract、Salary information and director and shareholder change documents。Even if the company is not trading,You should also check the local regulations for dormant companies first.、Specific requirements for zero reporting and record keeping,It is not appropriate to directly follow the handling methods of normal operating companies.。
Industry references:Accounting and Corporate Regulatory Authority of Singapore (ACRA):Company Annual Return。
Read more:Annual returns and public searches of Hong Kong companies:cost、Time and information disclosure scope、Hong Kong company accounting and tax filing:Audit time、Violation penalties and document preparation。