简体中文
 繁體中文
 English

After the establishment of the Hong Kong company,Need to be able to explain revenue、cost、assets、Accounting records of liabilities and fund flows,And submit profits tax returns and supporting documents as required by the tax bureau.。annual return、Business registration certificate renewal、Accounting audit and profits tax declaration are different matters,cannot replace each other。
Official verification:The regulatory scope covered by this article、Application Information and Ongoing Obligations,should beHong Kong Companies Registry Company Registration and Reporting InformationThe current published information shall prevail。
Do Hong Kong companies have to keep accounts?
Hong Kong’s Inland Revenue Ordinance requires persons operating a business to keep adequate records of income and expenditure,Enable assessable profits to be accurately calculated。Relevant business records are generally kept at least7 years。The company has no income、There is no business or bank account for the time being.,It should not be directly understood as not keeping accounting books or ignoring tax returns.。
Whether an audit report must be submitted
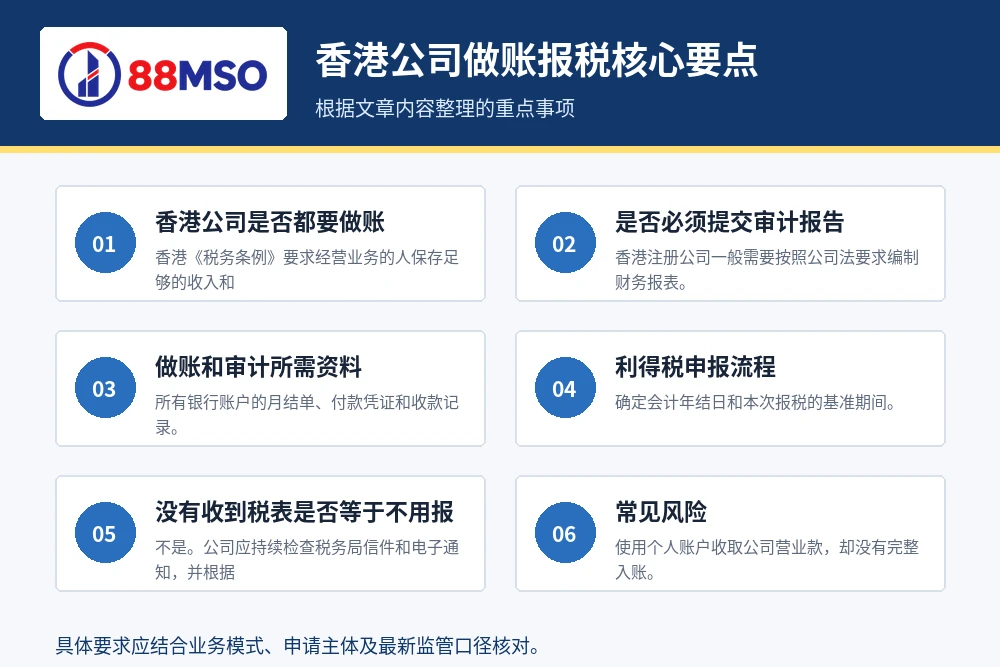
Companies registered in Hong Kong generally need to prepare financial statements in accordance with the requirements of the Company Law。Information from the tax bureau also states,Except for certain circumstances such as being in a dormant state according to law,Companies established in Hong Kong are usually required to support profits tax returns with audited financial statements。The actual filing also depends on the return type、Company Status and Inland Revenue Department Notices。
Information required for accounting and auditing
- Monthly statements for all bank accounts、Payment vouchers and collection records。
- sales contract、purchase contract、bill、Receipts and orders。
- salary、Mandatory Provident Fund、rent、Business trip、Freight and professional service fee information。
- shareholder loan、Description of transactions with affiliated companies and sources of funds。
- fixed assets、invest、Inventory and unsettled receivables and payables details。
- Company registration certificate、Business registration certificate、Charter、Annual Return and Change Documents。
- Audit report of previous year、Tax calculation sheets and correspondence from the tax bureau。
Profits tax filing process
- Determine the accounting year-end date and the base period for this tax return。
- Collate transactions throughout the year and complete banking、Checking correspondence between customers and suppliers。
- Prepare financial statements,Handle depreciation、stock、Accrued expenses and related transactions。
- Completion of applicable audit procedures by a certified public accountant。
- Prepare tax calculations、Profits Tax Return and Supplementary Forms。
- According to the notification from the tax bureau,Via the Business Tax website、Tax representative website or applicable method submission。
Does not receiving a tax form mean that you don’t have to file a tax return?
no。Companies should continue to check Inland Revenue Department correspondence and electronic notifications,and based on the date of establishment、Obligation to confirm past reporting status and actual operating conditions。The address was not updated and the tax form was not received.,Does not automatically eliminate the company's liability。
Common risks
- Use personal account to collect company business funds,but not fully recorded。
- Save only invoices,Don't save contract、logistics、Bank records and proof of source of funds。
- Record all shareholder transfers as income or expense,Causing tax calculation errors。
- Compiling multi-year accounts as the deadline approaches,Resulting in the inability to obtain customer or supplier certifications。
- Submit incomplete or untrue information,May trigger fines、Tax payment and further investigation。
Enterprises should organize their accounts on a monthly or quarterly basis,Instead of waiting to make up for it after receiving the tax form。For cross-border trade、Related party transactions、Virtual assets or multi-currency accounts,Clearer accounting and compliance records should also be established in advance。
official information:Hong Kong Inland Revenue Department:Keep business records;Electronic filing of profits tax returns
Related services:Hong Kong company registration
Dealing with both corporate and tax returns after the year-end
The company declaration and tax declaration involved in the accounting and tax filing of Hong Kong companies are not the same thing.。Lock the fiscal year end date first,Then list the accounts separately、financial statements、Audit or exemption judgment、Annual Return and Tax Return Submission Points,It can avoid mistaking the completion of one declaration as the completion of all compliance.。
Bank statements should be filed on a daily basis on a monthly basis、Sales and purchasing documents、contract、Salary information and director and shareholder change documents。Even if the company is not trading,You should also check the local regulations for dormant companies first.、Specific requirements for zero reporting and record keeping,It is not appropriate to directly follow the handling methods of normal operating companies.。
Industry references:Hong Kong Companies Registry:Company declaration official information。
Read more:UK VAT registration guide:tax rate、Application conditions and e-commerce platform submission method、Taxation after Japanese company registration、Maintenance fees and delivery documents。