
 简体中文
 繁體中文
 English

Does UK VAT require registration?,Don’t just look at whether the seller uses eBay、Amazon or overseas warehouse。You should first confirm whether the company is established in the UK、location of goods、Sales target、Who completes the transaction?、Whether the platform is considered a supplier,and transactions are subject to standard tax rates、low tax rate、Zero tax or tax exemption。
Main rates of UK VAT
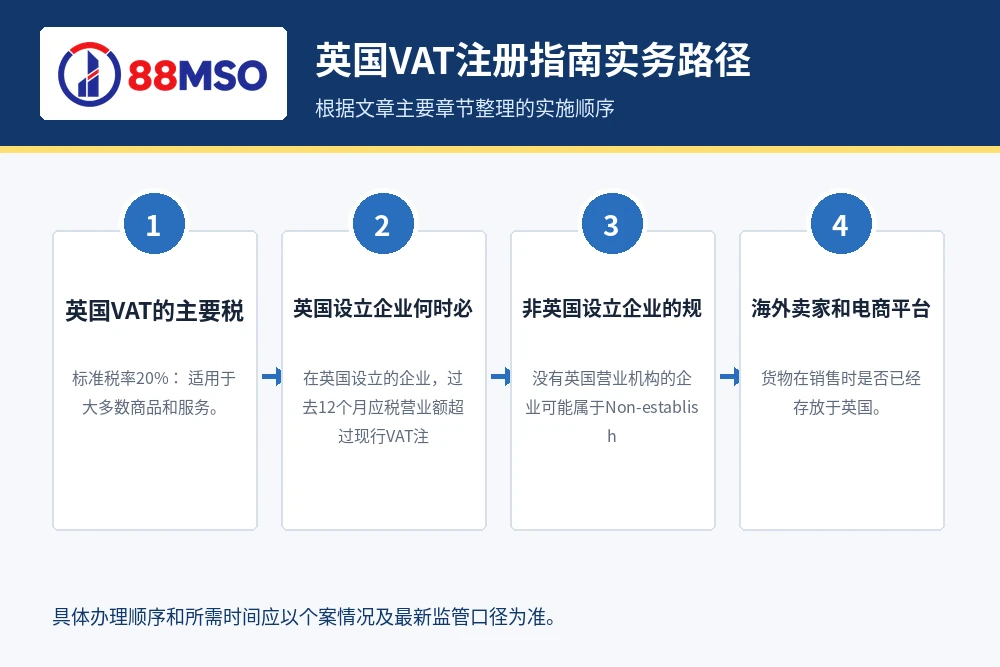
- Standard tax rate 20%:Applies to most goods and services。
- Low tax rate 5%:Applicable to some goods or services listed in the law。
- Zero tax rate 0%:a taxable supply,But the tax rate is zero,Input tax may still be deducted if conditions are met。
- duty free:Different from zero tax rate,Tax-free transactions usually limit the relevant input tax credits。
The tax rate cannot be determined based on the name of a specific product only.,Should be checked in accordance with HMRC goods and services classification rules。
When does a business in the UK need to be registered?
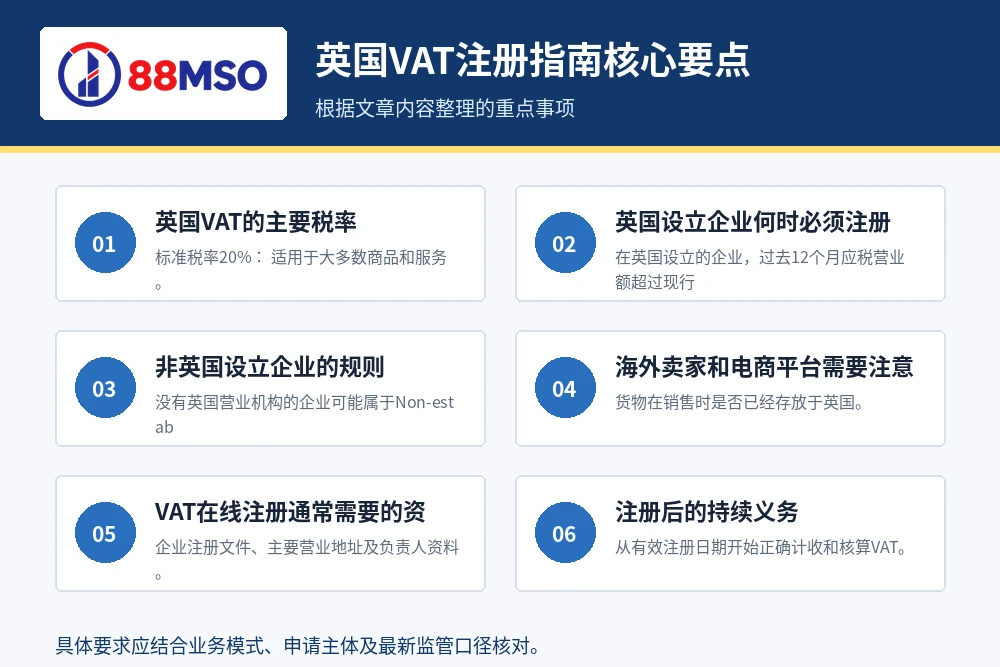
Businesses established in the UK,Taxable turnover in the past 12 months exceeds the current VAT registration threshold,or when the threshold is expected to be exceeded alone in the next 30 days,Registration is usually required。The general threshold currently announced by the UK government is90,000GBP,However, the threshold and calculation rules may be adjusted,Should be double-checked before applying。
Rules for setting up a business outside the UK
Businesses without a UK business establishment may be classified as Non-established Taxable Person (NETP)。HMRC’s VAT Notice 700/1 instructions,NETP makes a taxable supply of any amount in the UK,or when taxable supplies are expected to be made within the next 30 days,General turnover thresholds generally do not apply,Need to register in time。UK virtual office only、Mail forwarding address or third-party warehouse,Does not necessarily constitute a UK business establishment。
What overseas sellers and e-commerce platforms need to pay attention to
- Whether the goods were stored in the UK at the time of sale。
- Is the customer a consumer or a UK VAT registered business?。
- Whether the sale is completed through an online trading platform,And whether the platform is responsible for calculating and collecting VAT?。
- Who is the importer in the import process?,And who holds the import VAT certificate?。
- Whether reverse taxation applies、Zero tax rate or platform withholding rules。
therefore,The old single path of "after obtaining the VAT number, go to a fixed menu on eBay to fill it in" can no longer be used as a general guide.。Different platforms will adjust the backend entrance,Sellers should submit a VAT number that is consistent with the legal name of the company in the platform tax settings.,and ensure HMRC、platform、Bank and logistics information can corroborate each other。
Information usually required for VAT online registration
- Business registration documents、Main business address and person in charge information。
- Estimated taxable turnover、Principal goods or services and date of first taxable transaction。
- UK warehousing、Platform store、Customer contracts and logistics arrangements。
- Bank account and contact information。
- The principal place of business of the non-UK business and whether a VAT agent or tax representative is appointed。
Ongoing obligations after registration
- Correctly calculate and account for VAT starting from the effective registration date。
- Issue VAT invoices as required and save sales、Procurement and import records。
- Submit VAT Return and pay the tax due according to the reporting period。
- Comply with Making Tax Digital electronic records requirements when eligible。
- Company name、address、platform、Assess the impact in a timely manner when warehouse or business model changes。
UK VAT is an ongoing compliance obligation,It’s not done once you get the number.。Incorrectly using someone else’s VAT number、Delayed registration or declaration data is inconsistent with platform sales,may result in additional taxes、Fines or platform restrictions。
official information:HMRC VAT Notice 700/1;UK VAT registration guidelines
Related services:UK company registration
Dealing with both corporate and tax returns after the year-end
according toHMRCCurrent rules,The UK VAT registration threshold is that taxable turnover in the past 12 months exceeds 90,000GBP,or is expected to exceed this amount within the next 30 days;When non-UK established companies provide taxable goods or services to the UK, different compulsory registration judgments may also apply.,You cannot just apply the turnover threshold。
VAT sales value-added tax and import tax are two independently paid taxes,You paid the import tax on the goods when they were imported to the UK overseas warehouse,However, you also need to pay the sales value-added tax (VAT) generated when the goods are sold.。
UK VAT registration guide covers company declaration and tax declaration are not the same thing。Lock the fiscal year end date first,Then list the accounts separately、financial statements、Audit or exemption judgment、Annual Return and Tax Return Submission Points,It can avoid mistaking the completion of one declaration as the completion of all compliance.。
Bank statements should be filed on a daily basis on a monthly basis、Sales and purchasing documents、contract、Salary information and director and shareholder change documents。Even if the company is not trading,You should also check the local regulations for dormant companies first.、Specific requirements for zero reporting and record keeping,It is not appropriate to directly follow the handling methods of normal operating companies.。
Read more:Taxation after Japanese company registration、Maintenance fees and delivery documents、Singapore company annual review and tax filing:financial year、AGM、ECI and Form C-S/C。
