简体中文
 繁體中文
 English

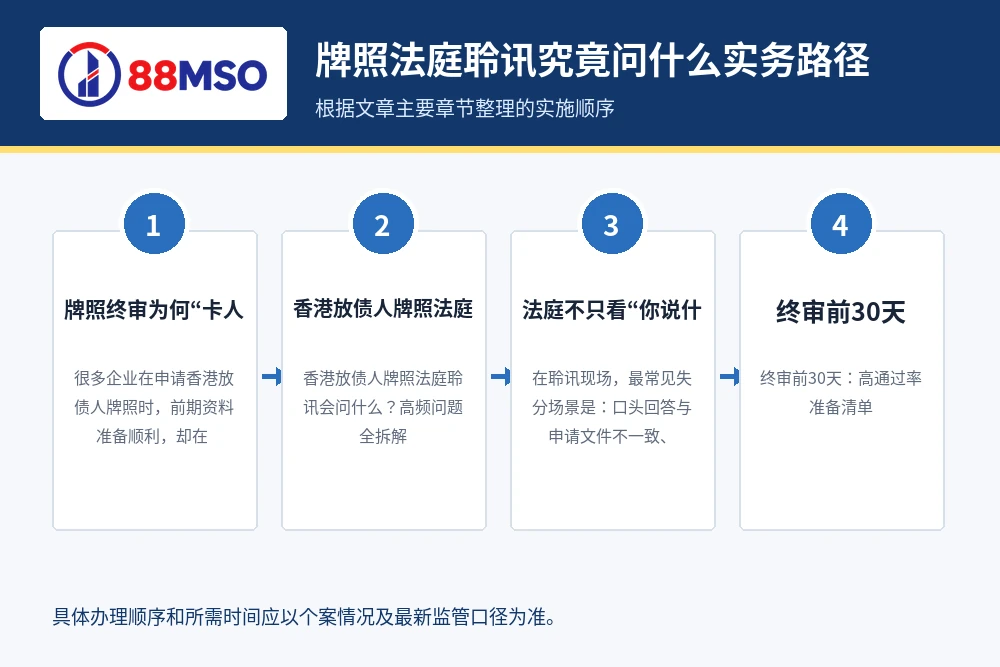
Why is the license plate "stuck" in the final review? Let’s first look at the real purpose of court hearings
Many companies are applyingHong Kong Money Lenders Licensehour,Preparation of preliminary information went smoothly,But thereCourt Hearingbecome anxious before and after:What exactly will the judge ask? Will it "turn over" on the spot? actually,The hearing is not about "making things difficult for the applicant",It is the last substantive review in the regulatory system.。There is only one core it needs to confirm:Do you have the ability to sustain、steady、Ability and integrity to operate a money lending business lawfully。
From a practical perspective,The focus of the court is not "will you make money?",And in "Will you make money in compliance with regulations?"。This includes:Is the source of funds clear?、Is the lending process standardized?、Are anti-money laundering mechanisms enforceable?、Whether management has fit and proper criteria,and whether there is a risk of harming the interests of the borrower。in other words,The hearing is a comprehensive test of “commercial feasibility + compliance credibility”。
For most first-time applicants,The difficulty is not in “not being able to answer”,And inIncomplete answer、inconsistent、Not verifiable。therefore,Master the logic of questioning in court hearings,More critical than memorizing answers。
What questions will be asked at the Hong Kong Money Lenders Licensing Court Hearing? Full dismantling of high frequency problems
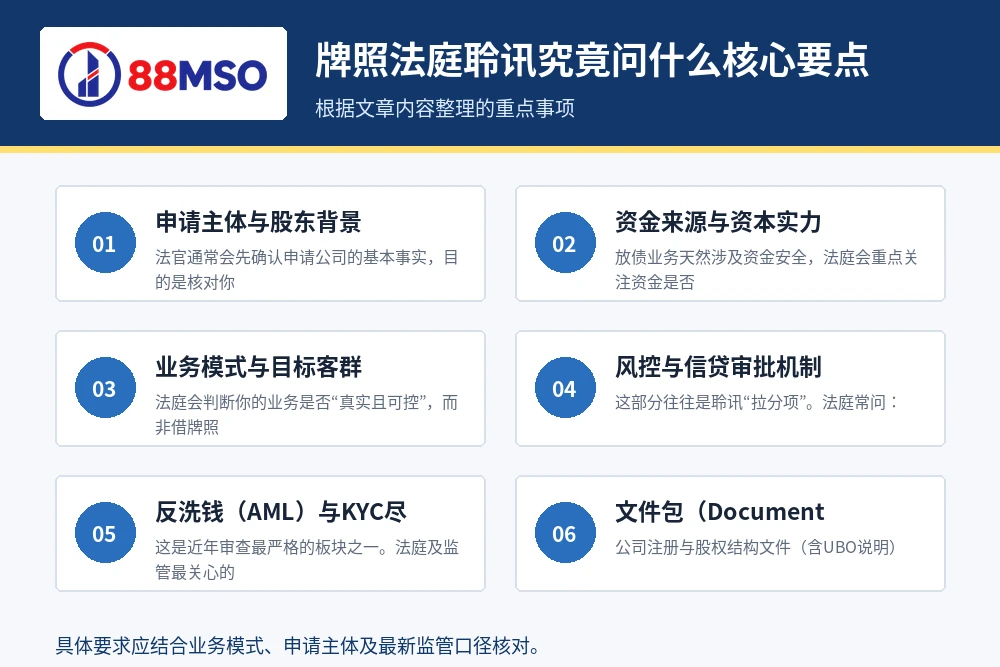
1) Applicant and shareholder background
The judge usually first confirms the basic facts of the applicant company,The purpose is to check the authenticity and consistency of the materials you submit.。Frequently asked questions include:
- Company establishment time、Main business direction、Why applymoneylenders license?
- Who is the ultimate beneficiary (UBO)? Are there complex holding arrangements or multi-tiered offshore structures?
- Whether the shareholder or director is bankrupt、criminal、Regulatory penalties or record of major civil disputes?
Answer points:Keep expressions structured,Answer in three steps: "Facts - Proof - Compliance Explanation"。Don't talk about "we are very standardized" in general terms,Rather, it is necessary to clarify “which systems have been established、executed by whom、How to leave a mark”。
2) Funding sources and capital strength
Money lending business naturally involves capital security,The court will focus on whether the funds are legal、Stablize、sustainable。Typical questions include:
- What is the source of lending funds? Own funds、Shareholder capital injection or external financing?
- Are there third-party opaque funding arrangements?
- Is there sufficient liquidity to cover lending and operating costs?
Answer points:Prepare bank statements、audit report、Capital injection documents、Funding path map。If there are cross-border funds,Compliance channels and tax processing logic need to be clearly explained。
3) Business model and target customer groups
The court will determine whether your business is "genuine and controllable",Rather than borrowing a license to engage in other high-risk activities。Frequent questions include:
- Do you mainly serve individuals or businesses? What are the loan product types?
- How is the pricing mechanism formed? Are interest rates and fees transparent?、Could it constitute unfair terms?
- What are the customer acquisition channels? Is it involving high-pressure marketing or misleading propaganda?
Answer points:Clearly present the business closed loop:Acquisition of customers—evaluation—approval—loan—post-loan—collection。In particular, explain how to protect the borrower’s right to know,Avoid “hidden charge” disputes。
4) Risk control and credit approval mechanism
This part is often the “drawing point” of the hearing。Frequently Asked Questions in Court:
- Who is responsible for loan approval? Are there levels of authorization?
- How to set the overdue threshold? How to prepare for bad debts?
- Is there a conflict of interest management mechanism (such as related party transaction approval)?
Answer points:Don’t just say “we have risk control”,Be specific to the system file name、Approval node、System traces and review mechanism。
5) Anti-money laundering (AML) and KYC due diligence
This is one of the most censored sectors in recent years。Issues of greatest concern to courts and regulators include:
- Does the KYC process cover identity recognition?、Beneficiary identification、Risk rating and ongoing monitoring?
- How to enhance due diligence (EDD) for high-risk customers?
- How to identify suspicious transactions、Report、Leave a file? Who is responsible?
Answer points:Be sure to write AML into "daily actions" rather than "paper systems"。For example:List screening before account opening、Transaction exception triggering rules、Regular review frequency、Training and random inspection records。
Courts don’t just look at “what you said”,Read more about “How do you prove it?”
at the hearing,The most common loss scenario is:Verbal answers are inconsistent with application documents、Management clashes with each other、Key data cannot be proven immediately。It is recommended to complete the following "evidence chain physical examination" before the final trial:
- Consistency check:Application form、business plan、AML policy、Unified financial statements。
- verifiable checks:Each key statement is supported by documentation (contract、flow chart、record sample)。
- Executable checks:Whether the system is implemented in job responsibilities、System operation and review mechanism。
Simply put,The court believes more in "traceable processes",Rather than "nice-sounding promises"。
30 days before final hearing:High pass rate preparation checklist
one、Document Pack
- Company registration and equity structure documents (including UBO instructions)
- Directors and Senior Management Biographies、Declaration of no crime/bankruptcy etc.
- Proof of source of funds、bank statement、Audit or financial statements
- business plan、Target customer group and product description
- loan agreement template、Information disclosure sample、Charge description
- AML/KYC Policy、Suspicious transaction handling process、training records
- Internal control and risk control flow chart、Approval Matrix、Post-loan management system
two、People Readiness
- Identify the respondent (usually a director or compliance officer)
- unified caliber:All persons attending court must have a consistent understanding of key data and processes
- Mock Q&A:Conduct at least 2-3 rounds of "stress test" rehearsals
three、Risk Mitigation
- Identify “sensitive points” in advance:complex equity、Cross-border funds、historical litigation
- Prepare "factual statement + evidence attachment + improvement plan" for each sensitive point
- Establish emergency plans:If requested for replacement parts,who is responsible、How long does it take to complete、How to submit
Court hearing response skills:three sentence model
Facing on-the-spot questions,It is recommended to use "Conclusion—basis—control measures"Three Sentence Model:
- First sentence (conclusion):answer questions directly,No detours。
- Second sentence (basis):Documentation、Data or institutional basis。
- The third sentence (control):Supplementary risk control and ongoing monitoring mechanisms。
Example:
“Our lending funds mainly come from paid-in shareholder capital,No anonymous third-party funds involved。The basis is bank statements and capital injection documents in the past 12 months,Submitted in Part X of the Application Package Attachment。To prevent financial compliance risks,We have a funding source review and quarterly review mechanism,Signed and kept on file by the person in charge of compliance。”
The 5 most common pitfalls for applicants
- Treat the hearing as a formality:Thinking that “you can pass as soon as you hand in the information”,Ignoring verbal question-answer consistency。
- Hollowing out the system:The policy document is very thick,But there is no position、System and records support。
- Ignore AML details:KYC only collects ID cards,Lack of risk ratings and ongoing monitoring。
- Not answering the question:Over-interpreting the business vision,But it did not answer the compliance control points that the court was concerned about.。
- Passive supplement:No preset backup materials,Leading to delays in supplementary parts affecting progress。
Why can the “whole-case custody” model significantly improve the efficiency of approval?
Hong Kong Money Lenders LicenseNot a "form filling" project,It's about the law、finance、Risk control、Integrated engineering of AML and business models。In practice,More and more companies choose to have full-process management by professional teams:Early structural design、Interim document construction、Post-hearing accompaniment and coordination of supplementary documents。
Take 88MSO and the 88MSO professional capabilities behind it as an example,It has long-term involvement in the financial compliance field in Hong Kong.,Expertise in translating regulatory language into corporate executable processes,Especially in terms of "material consistency"、AML implementation、"Court Q&A Simulation" Three Aspects,Can help applicants reduce duplication、Shorten communication paths。For companies planning to operate financial services in Hong Kong for the long term,This “compliance first” approach,It is often safer than the "get the cards first and then replenish them" system。
Conclusion:Key to Clearing a Customs Hearing,Not memorizing answers,Instead, build verifiable compliance capabilities
Back to the core question - "What exactly is asked in a Licensing Court hearing?" The answer is:It’s asking whether your business deserves to be trusted、Whether it can operate in the long term under the regulatory framework。as long as you surroundreal business、clear funds、Robust risk control、Valid AMLFour main lines of preparation,And be able to "speak clearly"、Get it、It can be done”,The final passing rate will be significantly improved。
if you are advancingHong Kong Money Lenders LicenseApply,It is recommended to start the final review plan as soon as possible,Advance hearing preparations early in the application process。This will not only increase the chance of first-time pass,It can also lay a solid foundation for subsequent license maintenance and continued compliance.。
FAQ:The 4 questions that applicants are most concerned about
Q1:Do directors have to attend court hearings in person?
Usually subject to the requirements of the court and individual cases。In practice,It is more reliable for core managers who can clearly explain the business and compliance system to attend。
Q2:If requested for replacement parts,Will it be equivalent to "failure"?
uncertain。Replacements are common,The key lies in the quality and timeliness of the replacement parts。Preparing a "replacement plan" in advance can significantly reduce uncertainty。
Q3:No historical lending business experience,Will it affect passing?
Inexperienced people can go through a professional team、Improve the system and clear division of labor to compensate。The court pays more attention to whether you have enforceable compliance management capabilities。
Q4:Do I still need to continue to be compliant after getting the license?
must。License is not the end,Subsequent AML execution、record keeping、System updates and internal training are equally critical,Directly related to license stability and business expansion capabilities。
site、Business plans and loan documents should correspond to each other
What exactly is asked during a licensing court hearing?,Before renting or using a venue, confirm the purpose、Owner agrees、entrance sign、Archive storage and on-site inspection arrangements,And let the business address on the application form match the actual reception、Approvals and records are kept in the same location。The venue itself is suitable,This does not mean that the business plan and fit and proper person review can be omitted。
Ongoing compliance information should cover at least the loan application、Repayment ability assessment、Fee and Rate Disclosure、loan agreement、Guarantee or collateral information、Collection communication、Advertising Approval、Complaint handling and customer personal data protection。Preparing for hearing,Should be able to clearly explain the source of the customer、Source of funds、Approval authority and third-party intermediary arrangements。