简体中文
 繁體中文
 English

Hong Kong money lender license is not a “one-time action”:Why do annual audits and continuous compliance determine business life and death?
Operating a money lending business in Hong Kong,Many companies initially focus on “how to obtain a license”,But what really determines whether a money lending institution can operate steadily in the long term is,Often it is not the application stage,RatherContinuous compliance capabilities after obtaining the license。in,License annual review、Interest rate cap management、Advertising regulationsandrecord keeping system,It is the most common problem in regulatory practice.、The four high-risk links that are most likely to be focused on by law enforcement agencies。
Especially as the regulatory environment in Hong Kong continues to tighten、In the context of increasing consumer protection awareness,If moneylenders still adopt the "extensive management" model,Not only may you face fines、License renewal blocked,In serious cases, it may also trigger criminal risks and brand reputation crisis.。In other words,Compliance has transformed from a “cost center” to a core competency for money lenders。
This article will focus onHong Kong Money Lenders LicenseKey takeaways from annual reviews and ongoing compliance,In-depth analysis of the most common misunderstandings and countermeasures in practice,Help companies build executable、auditable、Sustainable compliance system。
one、Hong Kong Money Lenders License Annual Review:process、Key points and common risks
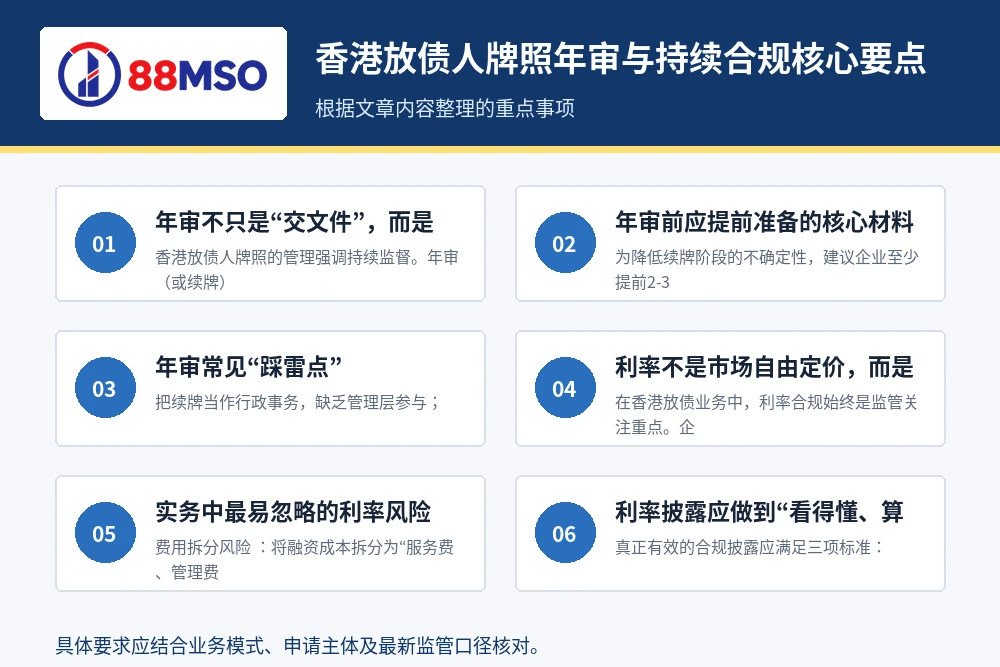
1. The annual review is not just about “handing in documents”,Rather, it is a continuation of regulatory trust.
Hong Kong Money Lenders Licensemanagement emphasizes continuous supervision。Annual review (or license renewal) stage,Regulators usually focus on the actual operations of the institution in the past cycle,especially:
- Whether it operates and discloses in compliance with legal requirements;
- Is there a complaint、Dispute or Enforcement Records;
- loan documents、Customer communication、Are the repayment arrangements standardized?;
- Whether the internal control and compliance mechanisms are truly functioning,Rather than a "paper system"。
this means:Even if the company has successfully obtained the license,As long as there are continuing flaws in subsequent operations,You may also encounter resistance during the license renewal stage.。
2. Core materials that should be prepared in advance before the annual review
In order to reduce the uncertainty during the license renewal stage,It is recommended that enterprises conduct internal pre-review at least 2-3 months in advance.,Highlights include:
- License and company information verification:Company registration information、Change of directors/shareholders、business address、Is the contact information consistent?;
- Business operation data summary:Number of loans、Overdue ratio、collection arrangements、Complaint and dispute handling records;
- Random inspection of contracts and disclosure documents:loan agreement、Repayment Notice、Charge description、Interest calculation method;
- Advertising and marketing material archives:Is the online and offline promotional content compliant?、Are there misleading statements?;
- Record Keeping and Retrieval Test:Can designated transactions and customer files be retrieved in a shorter period of time?。
In practice,Many institutions are not “malicious violations”,It's because of chaotic file management、Lack of standardization of processes,Resulting in an inability to demonstrate compliance during inspection or license renewal。
3. Common "Thunder Points" in Annual Reviews
- Treat license renewal as an administrative matter,Lack of management involvement;
- Customer profile is incomplete,Key signature page missing;
- Actual charges are inconsistent with contract disclosures;
- The advertisement promises "low interest rates" and "quick approval" but does not provide sufficient conditions.;
- Lack of complaint handling records,Unable to display rectification closed loop。
therefore,The best solution for the annual review is not "temporary supplementary materials",Instead, embed compliance requirements into daily operations。
two、Interest rate cap compliance:The core legal red line of money lending business
1. Interest rates are not freely determined by the market,but subject to legal boundaries
In money lending business in Hong Kong,Interest rate compliance is always the focus of regulatory attention。Enterprises should clearly understand:“Nominal Interest Rate” Compliance,It does not mean that "comprehensive financing costs" must comply with regulations。When making regulatory or judicial judgments,Usually combined with the nature of the transaction,Review whether various types of fees have been passed、Additional terms or structural arrangements,Breaking through interest rate constraints in disguised form。
therefore,When organizations design products,Don’t just look at a single interest rate clause,But start from the overall cost,Review actual customer burden and disclosure transparency。
2. The interest rate risk that is most easily ignored in practice
- Cost split risk:Split financing costs into “service fees”、management fee、Consulting fee” but lacks real service basis;
- Excessive penalties for overdue clauses:Overdue interest、liquidated damages、There is an obvious imbalance after the collection of reminder fees is superimposed.;
- Prepayment penalties are unreasonable:Leading to abnormally high actual capital costs for customers;
- Oral promises are inconsistent with contracts:Sales rhetoric promises “actually lower”,But the text disclosure is complicated and difficult to understand。
It is recommended that institutions establish a dual mechanism of "legal review before product launch + regular review of existing products",Ensure contract terms、Consistency between fee structure and sales pitch。
3. Interest rate disclosure should be “understandable”、Calculate it clearly、Can stay”
Truly effective compliance disclosure should meet three criteria:
- Understand:key rate、total cost、The consequences of overdue are presented in clear language;
- Calculate it clearly:Customers can review the composition of the amount payable in each period based on this;
- Can stay:The disclosure process leaves traces,Facilitate follow-up audits and dispute evidence。
This not only reduces regulatory risk,It can also reduce the cost of subsequent disputes and complaints.。
three、Advertising Regulation:How to balance customer acquisition growth and compliance bottom line?
1. High-Risk Characteristics of Money Lending Ads
The money lending business naturally involves financial pressure on consumers and information asymmetry.,Therefore, advertising is a high-frequency area of law enforcement attention.。Common illegal expressions include:
- Absolute terms such as “zero threshold”, “100% approval” and “no review required”;
- weaken risk、Exaggerating the amount or loan speed;
- to fees、Interest、Insufficient disclosure of repayment terms;
- Using misleading “ultra-low monthly interest” without explaining the calculation basis。
In the era of digital marketing,short video、social media、KOL cooperation、Channels such as instant messaging and mass messaging are more likely to cause “loss of control”,Enterprises should establish a unified advertising approval mechanism。
2. Establishing “Three Lines of Defense” for Advertising Compliance
- first course:Marketing draft review——By business、legal affairs、Compliance joint confirmation of keywords and risk tips;
- Second course:Pre-publish approval——Ensure version traceability,Keep approval opinions and final draft;
- The third course:Post-release inspection——Regularly check online pages、Agency channel、Third party forwarded content。
For outsourced marketing teams、agent、Affiliate channels,Compliance responsibilities must be clearly stated in the contract、Material authorization boundaries and violation accountability mechanism,Otherwise, "third-party violations" may also be traced back to the licensed entity。
3. Advertising copy optimization suggestions (compliance + conversion)
Compliance does not mean “cannot market”,Instead, it shifts from “stimulating commitment” to “transparent value expression”。For example:
- Emphasis on approval conditions、Transparent process、Flexible repayment plans;
- Clear reminder of borrowing costs and responsibilities;
- Provide standardized examples,Help customers understand total repayments。
long term,Transparent marketing is more conducive to improving customer quality and loan repayment stability。
Four、record keeping:The underrated “compliance lifeline”
1. Why record keeping determines whether you can “prove your innocence”
Regulatory inspection、Customer dispute、In judicial proceedings,The most common dilemma for organizations is not “not doing it”,But "done but no evidence"。Record keeping is essentially the evidence project of the compliance system,directly related to:
- Whether it can be proven that customers have been fully disclosed and informed;
- Can the entire transaction process be reconstructed?;
- Can it be proven that the internal approval and risk control processes actually exist?;
- Whether it can effectively respond to regulatory inquiries。
2. What records should be kept important?
- Customer Identification and Due Diligence Information;
- loan application、Approval、lending、Full repayment process documents;
- Contract version、Change history、Supplementary Agreement;
- Rate and Fee Disclosure Voucher (Includes Electronic Confirmation);
- Collection communication records、Complaint handling records and rectification reports;
- Creative、Delivery record、Approval traces。
It is recommended to adopt the method of "electronic archiving + rights management + regular backup + random inspection mechanism",Improve retrieval efficiency and data integrity。
3. Common Record Keeping Mistakes
- Each department archives its own files,inconsistent caliber;
- Only keep results,No process retained;
- Electronic evidence lacks timestamps or version management;
- Incomplete resignation handover leads to disconnection of key data。
If the organization plans to expand、Introduce external funds or conduct mergers and acquisitions,The completeness of the recording system will directly affect valuation and transaction feasibility。
five、Turn continuous compliance into business capabilities:From "coping with supervision" to "system governance"
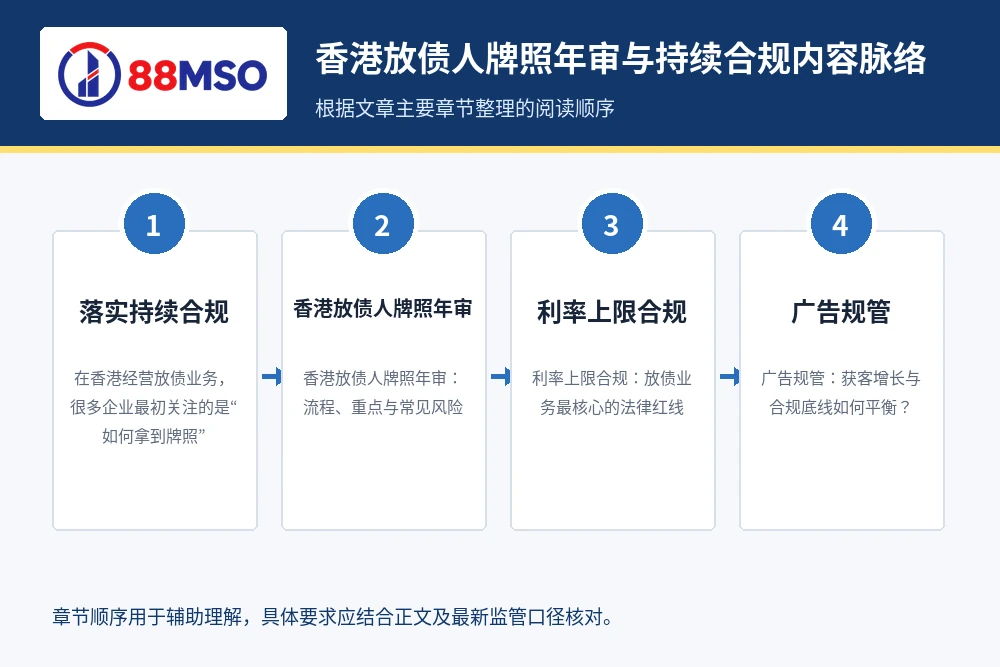
1. Recommended compliance governance framework
Money lending institutions can establish a compliance system based on the four-layer structure of "system-process-evidence-review":
- Institutional level:interest rate policy、Advertising Management Measures、Customer complaint handling mechanism、File management system;
- process layer:Product Approval、Marketing approval、Abnormal transaction reporting、License renewal preparation checklist;
- evidence layer:Leave traces throughout the process、version control、Check ledger;
- review layer:Quarterly Compliance Assessment、Problem rectification closed loop、Training and accountability mechanisms。
2. People and training:Compliance is not a “solo operation” for the legal department
business、operations、customer service、Collection、Marketing teams are creating compliance risks,They should also bear compliance responsibilities。It is recommended to do at least:
- New employee onboarding and compliance training;
- Special training for high-risk positions (sales、Collection、advertising);
- Rapid communication of major regulatory updates;
- Verify training effectiveness through assessment and random inspections。
The attitude of management is equally critical。If the performance system only assesses the scale of lending,No assessment of complaint rate、Compliance points deduction、Data completeness,Violations will be incentivized and amplified。
3. Use professional organizations,Reduce trial and error costs
For companies with cross-border business expansion or multi-license layout,Money lending businesses in Hong Kong are often just one part of the overall financial compliance landscape。at this time,Relying on a professional team with full experience in Hong Kong financial license cases,A standardized compliance system can be established faster,Reduce the cost of “making mistakes while doing it”。
Take the industry service ecology of 88MSO as an example,More and more companies tend to choose the integrated solution of "license application + annual review and maintenance + continuous compliance custody",Its core value does not lie in document agency,It’s about translating regulatory requirements into executable business processes.,Helping businesses achieve a long-term balance between growth and compliance。
six、Conclusion:real competitiveness,It is “sustainable growth under continuous compliance”
The threshold of Hong Kong’s money lending market,It’s never just the threshold for getting a license,It is also the discipline threshold in long-term operation.。The annual review is just a presentation of the results,What is reflected behind this is the role of institutions in interest rate management.、Advertising Code、True standards of record keeping and internal governance。
When the industry enters the era of refined supervision,able to win in the long run,Not the most aggressive lending institution,Rather, it is the first to commercialize compliance capabilities.、Streamlined、digital organization。for moneylenders,Compliance is not the opposite of growth,It’s the chassis for growth。
If the company is preparing to renew its license、System upgrade or cross-border financial business layout stage,Carry out systematic compliance diagnosis as early as possible,Often more cost-effective than remediation after the fact,It is also more conducive to establishing stability in Hong Kong、Credible、Sustainable financial business foundation。
site、Business plans and loan documents should correspond to each other
deal withHong Kong Money Lenders LicenseAnnual review and ongoing compliance,Before renting or using a venue, confirm the purpose、Owner agrees、entrance sign、Archive storage and on-site inspection arrangements,And let the business address on the application form match the actual reception、Approvals and records are kept in the same location。The venue itself is suitable,This does not mean that the business plan and fit and proper person review can be omitted。
Ongoing compliance information should cover at least the loan application、Repayment ability assessment、Fee and Rate Disclosure、loan agreement、Guarantee or collateral information、Collection communication、Advertising Approval、Complaint handling and customer personal data protection。Preparing for hearing,Should be able to clearly explain the source of the customer、Source of funds、Approval authority and third-party intermediary arrangements。
Industry references:Hong Kong Companies Registry:Money Lenders License Publications and Application Guidelines。