简体中文
 繁體中文
 English

Singapore bank account opening,Why can "complete information" still be rejected?
For many business owners、Cross-border e-commerce team、For Web3 project parties and family offices,Singapore bank accounts are almost the “standard” in global business layout。But the reality is:Many applicants even prepare company documents、Director's identity certificate、Proof of address,Still at DBS、Overseas Chinese (OCBC)、UOB was asked to make supplementary documents during the account opening review,Even rejected directly。
The core reason is not “whether there are materials”,But lies inCan the material fully prove your business logic?、Funding source transparency and ongoing compliance capabilities。The Singapore banking system’s role in anti-money laundering (AML)、Counter-Terrorism Financing (CFT)、Very high requirements in terms of tax transparency (CRS/FATCA) and cross-border transaction monitoring,Banks pay more attention to “Who are you?、what you do、Why do you need this account、How money will flow in the future”,rather than just “what did you submit?”。
This article will take a practical perspective,System comparison DBS、OCBC、UOB’s review thresholds and preferences,And give strategies to avoid pitfalls。For enterprises that have established financial structures in Hong Kong and Singapore at the same time,It will also be added how to use integrated compliance thinking to improve material consistency and audit communication efficiency.。
one、Let’s look at the underlying logic first:What exactly is the Bank of Singapore reviewing?
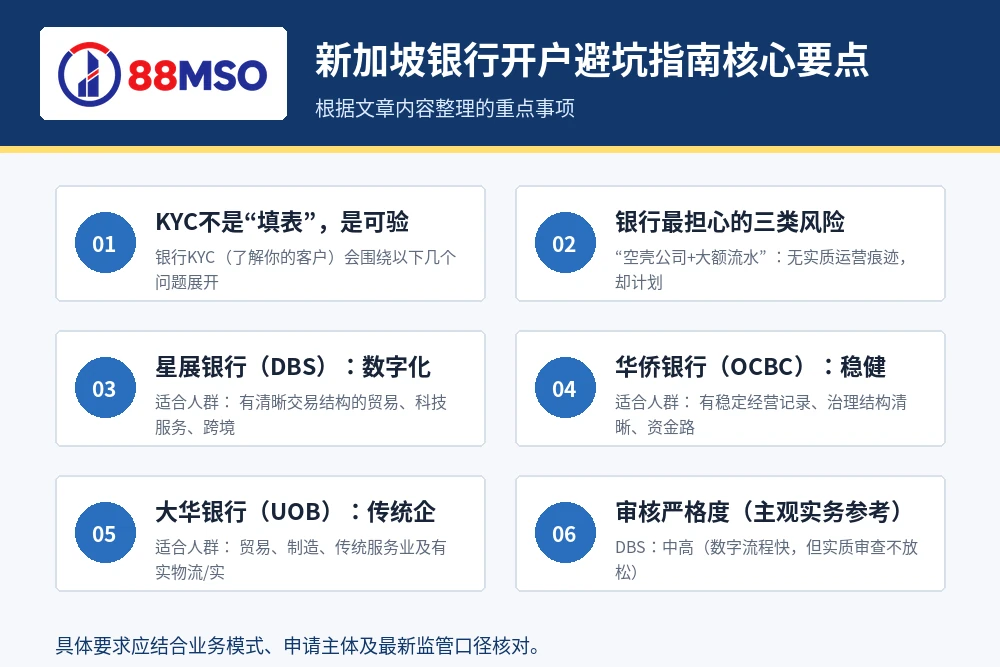
1. KYC is not “filling in a form”,Is a verifiable business portrait
Bank KYC (Know Your Customer) will focus on the following questions::
- Identity authenticity:director、shareholder、Is the beneficial owner (UBO) clearly traceable?;
- business authenticity:Does the company have real operating scenarios?、Upstream and downstream relationships、counterparty;
- Funding rationality:Source of funds、Transaction size、Whether the currency structure matches the business;
- Geographic and industry risks:Whether high-risk jurisdictions or sensitive industries are involved;
- Account Purpose Clarity:Why open an account in Singapore,Instead of opening an account at the original place of registration。
2. The three types of risks that banks are most worried about
- "Shell company + large turnover":No real traces of operation,However, he plans to make high-frequency and large-amount accounts in the short term.;
- The transaction chain is not closed loop:contract、bill、logistics、The repayment paths do not match each other.;
- Weak explanation ability:Management cannot clearly articulate the business model、gross profit logic、Customer source。
therefore,The point before opening an account is not to “prepare a few more documents”,Instead, build a set firstself-consistent、Verifiable、Traceablebusiness narrative。
two、DBS、OCBC、UOB review threshold comparison (practical perspective)
The following comparison is based on a summary of common market cases and review trends.。please note,different branches、account Manager、Application time windows may lead to differences in criteria,But the overall direction has reference value。
1. DBS Bank (DBS):Strong digitalization,But it has high requirements for business transparency
Suitable for the crowd:Trade with a clear transaction structure、Technology services、Cross-border e-commerce and regional headquarters enterprises。
Audit characteristics:
- High degree of online,The process experience is relatively friendly;
- to company website、business plan、The logical consistency of the transaction proof is more important.;
- Pay attention to trading forecasts and account usage details for the next 6-12 months。
Common replacement points:
- The difference between the initial flow rate and the declared flow rate is too large;
- Customers/suppliers are concentrated in high-risk areas,Lack of reasonable risk control instructions;
- Newly established company has no historical transactions,Unable to prove business implementation capabilities。
Tips to avoid pitfalls:Prepare transaction samples (contracts) in advance、bill、Bill of Lading/Proof of Service Delivery)、Official website business description、Organization chart and background description of actual controller,Avoid the “PPT company” image。
2. Oversea-Chinese Banking Corporation (OCBC):Steady and prudent,Emphasis on background penetration and rationality of use
Suitable for the crowd:Have a stable business record、Clear governance structure、Corporate and individual customers with relatively standardized funding paths。
Audit characteristics:
- Strict on UBO penetration,Especially multi-tier shareholding structures;
- Proof of source of funds、Tax resident information、High attention to historical bank transactions;
- If it involves cross-border complex structures,Often request a more complete due diligence package。
Common replacement points:
- The equity hierarchy is complex but lacks the ultimate beneficiary certification chain;
- Can’t explain “why it is necessary to open an account in Singapore”;
- Past compliance records (such as certain industry licenses、Regulatory Inquiries) Insufficient Disclosure。
Tips to avoid pitfalls:Prepare "Account Opening Purpose Statement",Clear regional settlement、Currency management、Business reasons such as centralizing payments in the supply chain;and prepare tax compliance statements simultaneously,Improve credibility。
3. United Overseas Bank (UOB):Traditional business friendly,However, detailed verification of transaction authenticity
Suitable for the crowd:trading、manufacture、Traditional service industries and small and medium-sized enterprises with evidence of physical logistics/real services。
Audit characteristics:
- Pay attention to physical business traces,Such as office space、team、Contract performance records;
- Be cautious about the "new company + high expected turnover" model;
- Tend to judge risks through closed trading loops,Rather than just looking at whether the file format is complete。
Common replacement points:
- Obfuscated information on upstream and downstream counterparties;
- Service businesses lack delivery credentials (such as project reports、acceptance form);
- The source of income deviates significantly from the industry average without explanation.。
Tips to avoid pitfalls:Prepare business vouchers that can be traced back to 3-6 months,Establish a "contract-invoice-payment-delivery" evidence chain,Reduce data inconsistencies and duplication of supplements。
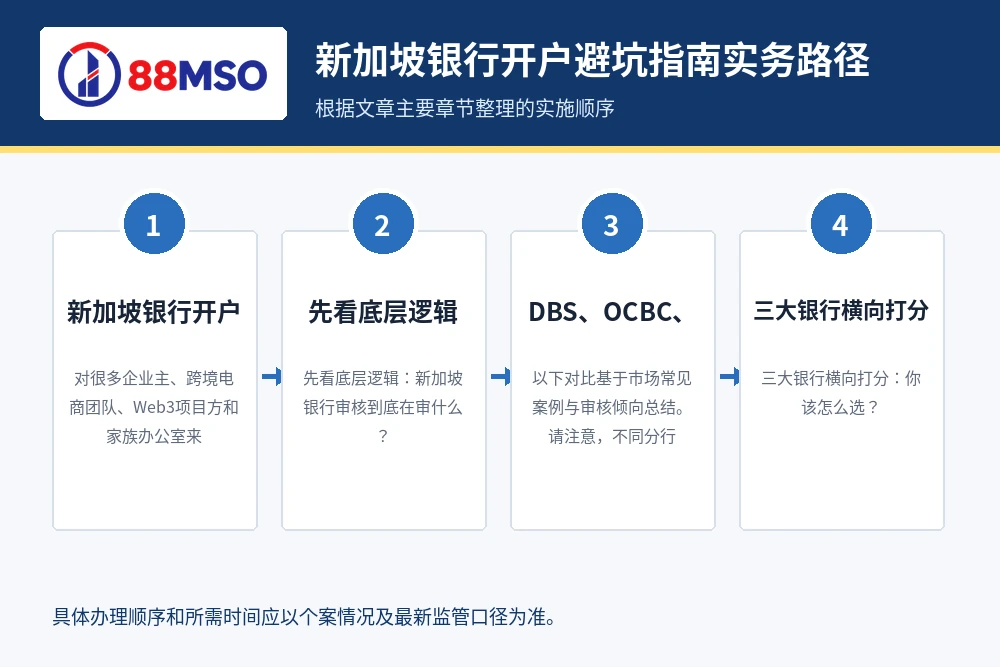
three、Horizontal scoring of the three major banks:How do you choose?
1. Audit rigor (subjective practical reference)
- DBS:Medium to high (quick digital process,However, substantive review will not be relaxed)
- OCBC:High (penetration and background verification are more detailed)
- UOB:Medium to high (emphasis on transaction authenticity)
2. Acceptance of new companies
- DBS:Medium (requires strong supporting documents)
- OCBC:Medium to low (preference is to have a business record)
- UOB:Medium (look at industry and transaction closed loop)
3. Tolerance for complex architecture
- DBS:Medium (the explanation is clear and can be advanced)
- OCBC:Medium (acceptable but please check carefully)
- UOB:Medium (focus on practical verifiability)
in conclusion:There is no “easiest” bank to open an account with,Only banks that are “more closely aligned with your business”。Wrong bank,No matter how much I prepare, I will make up for it again and again.。
Four、The 8 most common reasons for rejection
- Vain reason:Just say "internationalization needs",No specific transaction scenario;
- Revenue estimates are exaggerated:The amount declared in the first year far exceeds the size of the enterprise;
- Data is inconsistent:website、BP、The business descriptions in the account opening form are not uniform;
- UBO opaque:Hold on behalf of、Inadequate description of structures such as family trusts;
- Exposure to high-risk industries/regions:No supplementary risk control mechanism and compliance policy;
- Lack of historical credit:No bank statement or audit basis;
- Insufficient preparation for interview:The person in charge gave inconsistent answers;
- Ignore follow-up maintenance:Only focus on account opening,Not paying attention to ongoing account compliance。
five、Account opening information list:Not just "Qi",More importantly, “be able to speak clearly”
Enterprise Basic Package
- Company registration certificate、Charter、annual return documents;
- Proof of identity and address of directors/shareholders/UBO;
- Organization chart (penetrated to natural persons)。
Business proof package
- core contract、bill、Order、Proof of logistics or delivery;
- Official website、Product information、Customer portrait description;
- Revenue in the past 6-12 months (if any) and future transaction forecasts。
Compliance Information Packet
- Source of Funds;
- Source of Wealth,Targeted at high net worth);
- Tax resident information and CRS/FATCA self-declaration;
- Provide a summary of AML/KYC internal policies when necessary。
six、Interviews and questionnaire responses:The “last mile” that determines success or failure
Many applications were rejected,Not because the company is bad,It’s because the interview answers are “like memorizing a manuscript”。What banks want to see is that management has real control over the business。It is recommended to practice in advance around the following issues::
- What countries/customer types does your main revenue come from?
- What is the average transaction amount per transaction and the number of transactions per month?
- Why choose Singapore,Rather than Hong Kong or other regions?
- Does it involve third-party collection and payment? How to control money laundering risks?
- If transaction volume increases rapidly,How to upgrade internal compliance?
The answer principle is:reality、specific、Can be verified by documents。Vague answers often trigger more scrutiny。
seven、From "account opening successfully" to "long-term availability":Account maintenance is the real test
Many companies experience account restrictions 3-6 months after opening an account.,The reason is usually that the transaction deviates from the declared purpose、Abnormally large amount of money deposited into account、Counterparty risks increase or data is not updated in a timely manner。It is recommended to establish a quarterly compliance physical examination mechanism:
- Regularly review counterparty KYC;
- Secure Payment P.S.、contract、Invoice consistent;
- Proactively notify account managers when business changes occur;
- Keep directors updated、shareholder、Address and beneficiary information。
For plans that also hold a Hong Kong financial license (such as MSO、SFC related licenses、moneylenders or insurance brokers) and conduct cross-border capital business,Bank compliance and license compliance must be linked。Only by placing the account opening strategy within the larger regulatory framework,The account will be stable、sustainable。
eight、Practical suggestions for Hong Kong + Singapore dual hub enterprises
More and more overseas companies adopt the dual-center model of "Hong Kong operation/license platform + Singapore settlement and wealth management"。This structure is not as simple as opening an additional account.,But ask:
- Clear ownership of legal persons and business contracts,Avoid misallocation of funds;
- Cross-border payment paths are consistent with tax declarations;
- AML policies in different jurisdictions can be bridged;
- Key positions (compliance、finance、Risk control) can respond to bank reviews with a unified approach。
at this point,A professional team with practical experience in financial compliance in Hong Kong,It is often better to help companies upgrade "account opening materials" to "regulatory acceptable business logic"。Take the professional service capabilities connected to 88MSO as an example,Many customers are not lacking documents,But lack of license plate、bank、Overall compliance design from tax to cross-border transactions。Front-end preparation done right,Back-end maintenance costs will be significantly reduced。
FAQ:Frequently asked questions about opening a bank account in Singapore
Q1:Can a new company directly open a Singapore company account?
Can,But it is more difficult than companies with business records。You need a verifiable contract、Order、Team configuration and funding planning to demonstrate that “real operations are about to happen”。
Q2:Do I have to be present in person?
Depends on bank and specific application。Some processes can be carried out remotely,However, key nodes may still require interviews or video due diligence by directors/actual controllers.。
Q3:After being rejected by a bank,Can I still apply to another one?
Can,However, it is not recommended to “blind investment” immediately。Review the reasons for rejection first,Correct data logic and business narrative,It will be safer to choose a matching bank。
Q4:Is there a big difference between the review of individual accounts and corporate accounts?
Corporate accounts pay more attention to business authenticity and closed-loop transactions;Individual households pay more attention to the source of wealth and tax transparency。If a high-net-worth individual’s trading behavior is close to business activities,will also be subject to strict scrutiny。
Q5:How to reduce duplicate parts?
three steps:First do the pre-examination (identify risk points) → then do the material stratification (basic package/business package/compliance package) → finally do the interview drill (unified caliber)。This is much more efficient than "submit first and then add parts"。
Conclusion:Opening an account is not the end,Compliance management is the moat
DBS、OCBC、UOB is not absolutely "easy to drive",There are only differences in preferences for different customer profiles。What really determines the outcome,is whether you can use a set of materials that can withstand penetrating scrutiny,Prove business authenticity、Funding transparency、Risk controllable。
For companies planning to expand into Hong Kong and overseas markets,Singapore bank account openingShould be considered as part of an overall compliance strategy,rather than a single administrative action。Put KYC、AML、Tax transparency and business growth on the same picture,You get more than just an account,It is a long-term sustainable international capital channel.。
Account opening materials must form a complete chain of financial evidence
When preparing a guide to avoid pitfalls when opening a bank account in Singapore,Banks usually structure their companies、actual controller、business contract、Customers and Suppliers、Expected trading country、Single and monthly amounts and funding sources are judged together.。website、bill、contract、If the written and verbal instructions conflict with each other,Easily trigger patchwork or enhanced due diligence。
High-risk industries should prepare separate licenses or registration certificates、Anti-Money Laundering System、Customer access criteria、Sanctions Screening and Transaction Monitoring Instructions,and evidence of source of funds and source of wealth for major transactions。Remote account opening does not mean less review;Unexplained collection and payment、Short-term large-amount postings and transactions inconsistent with reported business,You should adjust the process before opening an account。
Industry references:Monetary Authority of Singapore Directory of Financial Institutions。
Read more:Hong Kong and Shanghai Banking Corporation (HSBC) corporate account interview:Account opening information and review points、Swiss private bank account opening process:Account requirements for high net worth clients and offshore financial institutions。