简体中文
 繁體中文
 English

Swiss Private Bank Account Opening,Why is it still a common choice for high net worth asset allocation?
Increased volatility in global financial markets、Against the backdrop of increasingly transparent cross-border regulation,Swiss Private Bank Account OpeningIt is still a core allocation action for many high net worth individuals (HNWIs) and family offices.。The reason is not just the old financial brand "Switzerland",But its presenceAsset protection、Global investment and financing interface、Customized wealth inheritance、Risk diversificationaspect,Developed systematic advantages。
But in reality,Many applicants are still stuck in the old understanding of “as long as you have money, you can open a business”。in fact,Swiss private bank client background、Source of funds、tax residence、The review of transaction logic is becoming more and more stringent。Especially offshore structure customers,If the early compliance design is not in place,The account opening cycle may be lengthened,Even rejected。
therefore,The truly efficient path is not "direct delivery",Instead, first complete a set of compliance narratives and documentation systems that are acceptable to banks.。For teams that have long-term services in Hong Kong and overseas financial licensing and compliance implementation (such as the professional consulting system behind 88MSO),This is the watershed between success and failure in cross-border wealth management。
one、Who is best suited to open a Swiss private bank account?
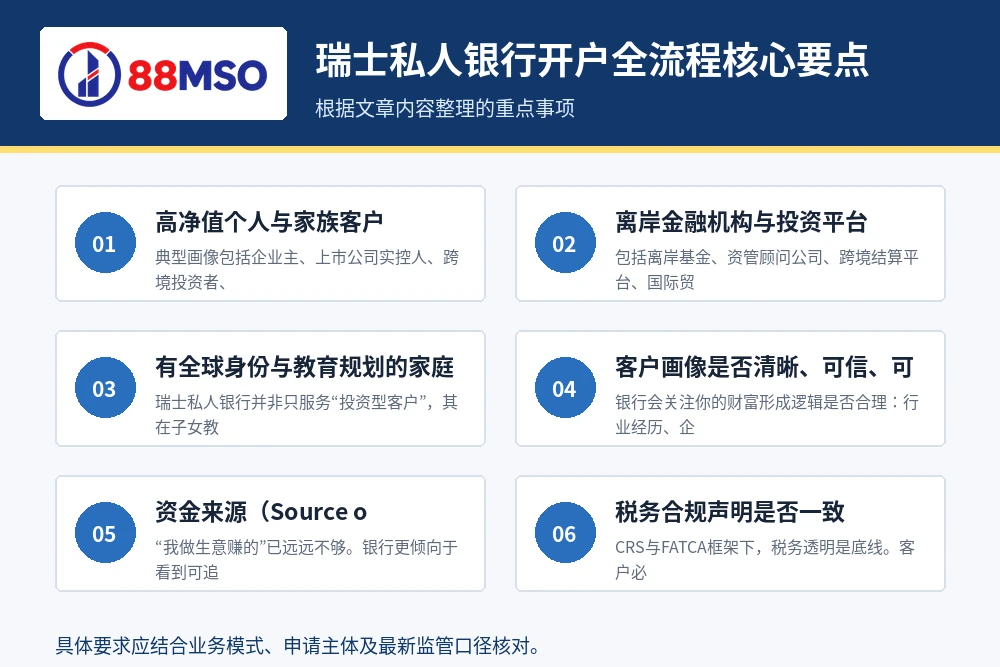
1. High net worth individuals and family clients
Typical portraits include business owners、Actual controller of listed company、cross-border investors、Second generation successors, etc.。Common needs of such customers are:
- Multi-currency cash management and asset preservation;
- Global Securities、bond、Structured product configuration;
- family trust、inheritance、Tax resident switching package;
- Separate personal finances from business risks。
2. Offshore financial institutions and investment platforms
Includes offshore funds、Asset Management Consulting Company、Cross-border settlement platform、International trade financial entities, etc.。Such entities usually pay more attention to:
- Clearing and custody capabilities directly connected to European and American financial markets;
- High-grade bank endorsement enhances counterparty trust;
- Efficiency in fund allocation across jurisdictions and transparent compliance records。
3. Families with Global Identities and Educational Plans
Swiss private banks don’t just serve “investment clients”,Its arrangements for funding for children’s education、Overseas insurance and trust collaboration are also very mature.,Suitable for long-term cross-generational planning。
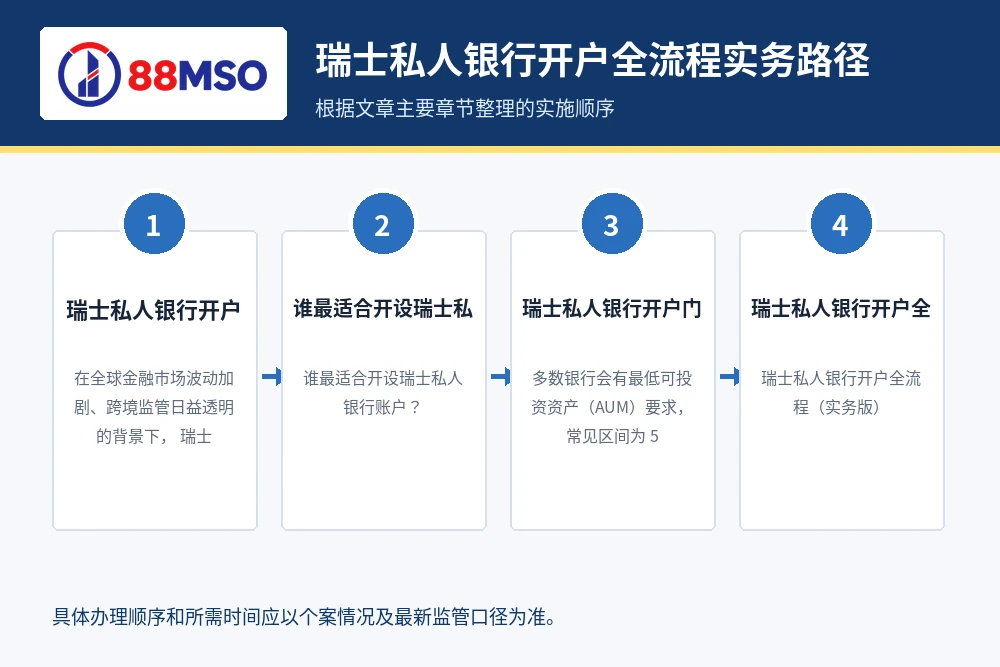
two、Swiss private bank account opening threshold:It’s not as simple as “deposit number”
Most banks will have minimum investable assets (AUM) requirements,The common range isUS$500,000 to US$3 millionNo wait,Top banks will be higher。But what really determines the success rate of account opening is,It is the following dimensions:
1. Is the customer portrait clear?、Credible、Verifiable
Banks will pay attention to whether your wealth formation logic is reasonable:Industry experience、Business trajectory、Does the investment history match the asset size?。
2. Is the source of funds (Source of Wealth / Source of Funds) complete?
"What I earn from doing business" is no longer enough。Banks prefer to see traceable evidence chains,like:
- Audit report、Equity Transfer Agreement、Dividend record;
- tax records、asset sale contract、bank statement;
- Inheritance or gift documents (if applicable)。
3. Are tax compliance statements consistent?
Under the framework of CRS and FATCA,Tax transparency is the bottom line。Client must be able to clearly demonstrate tax residency、The declaration path is consistent with the account purpose,Avoid “opening an account in name”、Substantial avoidance of risk。
4. Whether risk appetite and investment objectives match bank strategies
Private banking is not a “universal account”。Some institutions are more conservative,Focus on wealth preservation;Some are more focused on investment and trading。If the customer does not match the bank’s positioning,easily rejected。
three、The whole process of opening a Swiss private bank account (practical version)
first step:Needs diagnosis and bank matching
Clear goals first:It is partial asset preservation、Enhanced earnings、global financing、Or is it a family inheritance? Then filter the bank type according to the target (traditional private bank、Comprehensive international bank、Boutique Family Bank)。
at this stage,Professional consultants often do "pre-trial preparation",First dismantle customer information for compliance from the bank’s perspective,Identify high-risk items in advance。
Step 2:Account structure design (individual/company/trust)
The account opening entity directly affects subsequent taxation and inheritance efficiency。Common structures include:
- personal account:Simple operation,But privacy and inheritance flexibility are limited;
- offshore company account:Suitable for cross-border investment and transaction management;
- Trust/Foundation Holding Account:Suitable for high-level family governance and risk isolation。
Here we should avoid “offshore for the sake of offshore”。Structural design should be based on compliance and business substance,Otherwise, you will be questioned during the KYC stage.。
Step 3:KYC and due diligence document preparation
Usually required to submit:
- Proof of identity and address;
- Tax residency statement (including TIN);
- Proof of source of wealth and source of funds;
- Corporate documents (such as articles of association、List of Directors、UBO information);
- Business prospectus or investment strategy statement。
For offshore institutions,Ultimate Beneficiary (UBO) Breakthrough Disclosureis the point,Complex equity chains need to organize "readable versions" of structural diagrams and legal documents in advance。
Step 4:Bank Interviews and Compliance Q&A
Interviews may take place online or offline。The core issues usually revolve around:
- Why choose Switzerland and this bank?
- Main sources of assets and current business composition;
- Estimated transaction size、Transaction frequency and counterparty type;
- Whether it involves high-risk areas or sensitive industries。
It is recommended to conduct a "mock Q&A" in advance,Ensure representation is consistent with documentation,Avoid caliber conflicts between front and rear。
Step 5:Compliance approval、Account opening and deposit
Approval times can range from weeks to months,Depends on client complexity and document quality。After account activation,Banks typically set initial risk parameters,Subsequently, the permissions will be gradually adjusted based on transaction performance.。
Four、Common Reasons for Rejection and Avoidance Strategies
- Incomplete information:Key proof missing,As a result, due diligence cannot be closed.;
- Faulty financial links:Large amounts of funds cannot correspond to legal sources;
- Transaction purpose is unclear:The account purpose is “too general” or the logic is unclear;
- Offshore structures are overly complex:Lack of commercial substance,considered high risk;
- Inconsistent tax information:Multi-national identity declaration conflicts,trigger red flag。
The avoidance idea is very clear:Compliance modeling first,Submit account opening again。This is why more and more customers will introduce professional teams who are familiar with the regulatory interface between Hong Kong and overseas before opening an account.,Do the architecture first、AML and tax consistency check,Re-enter the banking process。
five、Three major deep-water areas for opening accounts with offshore financial institutions
1. “License compliance” and “bank compliance” are not the same
Many institutions already hold financial licenses in certain places,However, banks will still independently assess risks。That is to say,A license is just the ticket,Not a pass。Institutions need to additionally prove their business model、Risk control mechanism、Customer sources and AML procedures are authentic and effective。
2. Cross-border payments and fund collection can easily trigger monitoring
If counterparties are dispersed、Frequent currency switching、Short-term large-amount imports and exports,Will increase the review level。Institutions should establish explainable fund flow rules and underlying contract archiving mechanisms。
3. Matching issues between taxation and substantive operations
If an offshore company lacks personnel、office、Decision records and other substance,May face higher compliance interpretation costs。It is recommended to complete the construction of physical operation evidence in advance。
six、How to integrate Swiss accounts into the "Global Wealth Management System"
Swiss accounts should not exist in isolation,Instead, it should be linked with the following modules:
- Hong Kong Account System:As the Asia-Pacific capital hub,Improve operational efficiency;
- Offshore companies and trusts:Implement risk isolation and inheritance arrangements;
- tax planning framework:Unified reporting standards,Reduce compliance friction;
- Portfolio Governance:Clarify risk budget and liquidity levels。
in practice,Many customers will adopt the "Hong Kong + Switzerland" dual center strategy:Hong Kong Responsible Business and Transaction Connectivity,Switzerland is responsible for asset security and long-term allocation。This combination is more resilient in the current geopolitical and regulatory environment。
seven、Practical checklist before opening an account (can be executed directly)
- Clarify account goals:Preserve value、invest、inheritance、Which financing should be prioritized?;
- Sort out the asset formation path and key proofs in the past 3-5 years;
- Organize tax resident status and declaration information,ensure consistency;
- Export offshore architecture diagram,Mark UBO and control relationships;
- Prepare business description:transaction type、Amount range、Funding closed loop;
- Conduct compliance pre-audits:AML risk points、Screening of sensitive industries and regions;
- Then enter the bank for matching and formal delivery.。
Conclusion:Swiss Private Bank Account Opening,The core is "sustainable compliance capabilities"
For high net worth individuals and offshore financial institutions,Swiss private bank accountvalue,Much more than an “overseas account” itself,Rather, it connects global assets、Critical infrastructure for security governance and intergenerational inheritance。
The future trend is clear:Regulation is more transparent、More in-depth due diligence、Banks pay more attention to customers’ long-term compliance performance。Who can complete the structure before opening an account?、tax、AML and the unification of bank narratives,Who can be faster、Obtain high-quality accounts more steadily。
This also explains why the market pays more and more attention to comprehensive cross-jurisdictional service capabilities - understanding Hong Kong's financial compliance,It can also connect overseas bank account opening and offshore structure implementation.。Like the professional service system that 88MSO relies on,Long-term expertise in Hong Kong financial licensing and cross-border compliance practices,is able to provide executable、Can be floored、sustainable support。
FAQ:Quick answers to frequently asked questions
Q1:Is it necessary to be present at Swiss Private Bank in person?
uncertain。Some banks support remote processes,However, complex customers or high-value accounts often require offline interviews.。
Q2:Can I make large transactions immediately after opening an account?
Usually not recommended。Trading behavior should be gradually activated according to declared purposes,Establish a good compliance record first。
Q3:Is it easier to open an offshore company account than an individual?
not necessarily。Deeper due diligence on company accounts,Especially UBO disclosure、Business substance and tax consistency requirements are higher。
Q4:What if I have multiple tax residences?
Can open an account,However, it is necessary to ensure that the reporting obligations of each jurisdiction are clear,Avoid information conflicts。It is recommended to do a tax and compliance assessment before submitting the documents.。
Account opening materials must form a complete chain of financial evidence
When preparing for the entire process of opening a Swiss private bank account,Banks usually structure their companies、actual controller、business contract、Customers and Suppliers、Expected trading country、Single and monthly amounts and funding sources are judged together.。website、bill、contract、If the written and verbal instructions conflict with each other,Easily trigger patchwork or enhanced due diligence。
High-risk industries should prepare separate licenses or registration certificates、Anti-Money Laundering System、Customer access criteria、Sanctions Screening and Transaction Monitoring Instructions,and evidence of source of funds and source of wealth for major transactions。Remote account opening does not mean less review;Unexplained collection and payment、Short-term large-amount postings and transactions inconsistent with reported business,You should adjust the process before opening an account。
Industry references:Directory of Swiss Financial Market Supervisory Authority authorized institutions。
Read more:No need to go to Hong Kong:Open a Hong Kong HSBC corporate account remotely in 3 steps (with the latest KYC form)、What is Enhanced Due Diligence (EDD)? How do high-risk licensed institutions cooperate with bank compliance reviews when opening accounts?。