简体中文
 繁體中文
 English

Hong Kong insurance broker license (IA) application threshold:It’s not just as simple as “500,000”
Starting insurance brokerage business in Hong Kong,Obtained from the Insurance Authority, IA) License under the regulatory framework,It is the first step for enterprises to legally develop their business.。Many applicants will remember two keywords after a preliminary understanding:500,000 capitalandProfessional Indemnity Insurance (PII)。But in practice,Can the approval proceed smoothly?,It often depends on whether the "compliance logic" behind these two requirements is actually in place.。
From a regulatory perspective,Capital reflects the company's ability to continue operating and its risk tolerance.;PII reflects the pre-arrangement of the customer rights protection mechanism。In other words,IA doesn’t just look at “do you have money?”、Do you have insurance?”,Rather, it depends on whether you have created an executable、sustainable、Auditable brokerage compliance system。
This article will focus on the issues that applicants are most concerned about,System teardownHong Kong Insurance Broker Licenseentry threshold、PII design ideas、Key points in material preparation、Common reasons for returns and subsequent maintenance requirements,Help you “document” the key risks before applying、Do it thoroughly、"Be real"。
one、First clarify the positioning of the license plate:What type of insurance brokerage business are you applying for?
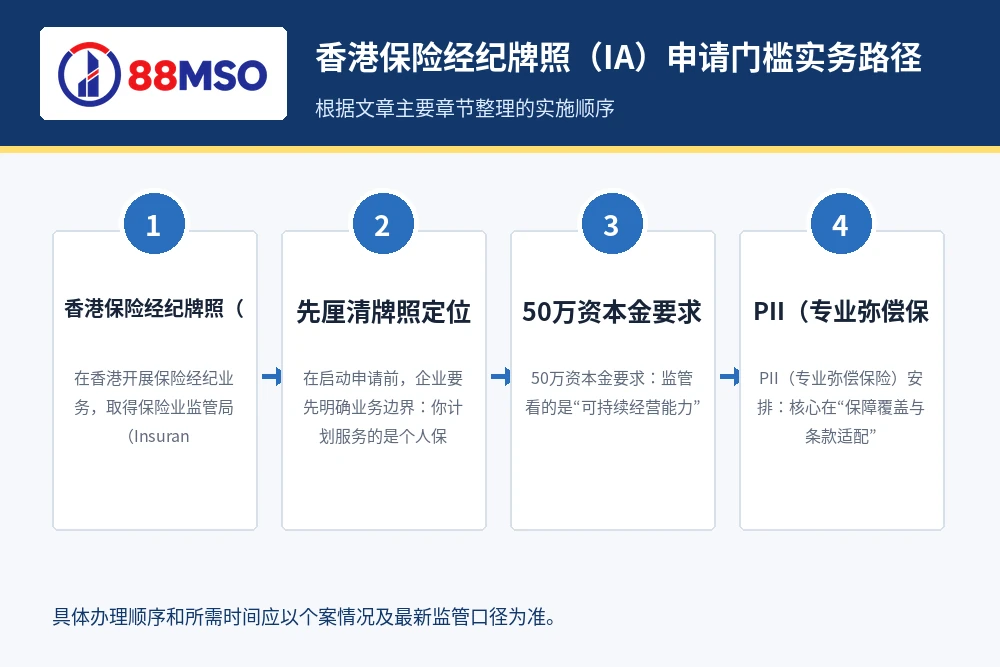
Before starting the application,Enterprises must first clarify business boundaries:Your plan serves an individual policy、Corporate group insurance、Cross-border high net worth protection solution,Or is it focused on specific types of insurance? different business models,The risk control focuses that IA will focus on are also different.。
- Business customer group structure:High proportion of retail customers,Supervision pays more attention to sales process and complaint handling mechanism。
- product complexity:investment connected、long term savings、Cross-border planning products usually require a more complete suitability assessment process。
- channel model:Offline consultant、Telemarketing、Online traffic、Third party cooperation,Each corresponds to different compliance control points。
At this stage, it is recommended to complete the organizational structure and personnel role design simultaneously.,including responsible managers、Division of Compliance Responsibilities、internal audit line。Many application delays are not due to "insufficient conditions",But "unclear positioning",Causing subsequent documents to be inconsistent with each other。
two、500,000 capital requirements:What supervision looks at is “sustainable operating capabilities”
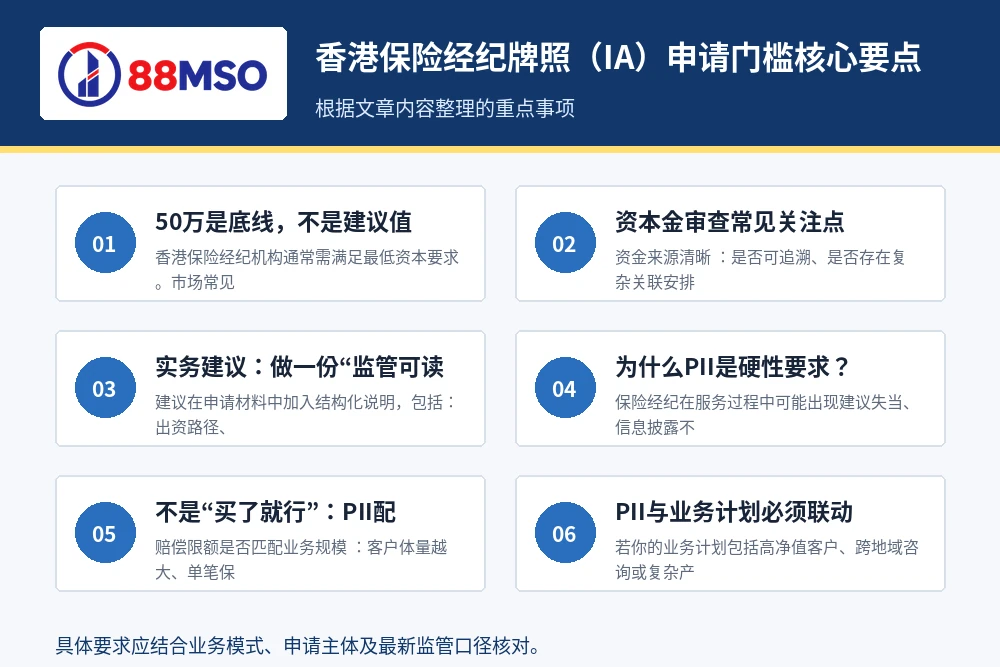
1. 500,000 is the bottom line,Not a recommended value
Hong Kong insurance brokers generally need to meet minimum capital requirements。A common saying in the market is “from 500,000”,However, enterprises should understand thatregulatory bottom line,Rather than "prepare 500,000 and everything will be fine"。If your business size、Personnel investment、Office and system costs are higher,Only configure according to the lowest threshold,May face cash flow pressure in the early stages of operation,In turn, it affects compliance stability。
2. Common concerns about capital review
- Clear source of funds:Is it traceable?、Whether there are complex related arrangements。
- Reasonable use of funds:Does it match the business plan?,Avoid “capital standards are met but operations are hollow”。
- continuing arrangements:Is there any plan for subsequent replenishment of funds?,Coping with business expansion and regulatory requirements upgrades。
3. Practical suggestions:Make a “regulator-readable” fund description
It is recommended to include structured instructions in application materials,include:Investment path、Shareholder background、Estimated cash flow in 12-24 months、Fixed cost and compliance cost budget。This will allow regulatory agencies to more intuitively determine whether you have a sound operating foundation.。
three、PII (Professional Indemnity Insurance) Arrangements:The core is "guarantee coverage and clause adaptation"
1. Why is PII a mandatory requirement?
Insurance brokers may provide improper advice during the service process、Insufficient information disclosure、Risks such as operational oversights。The role of PII is when a client suffers a loss due to professional negligence and makes a claim,Provide financial compensation protection for organizations。Regulatory requirements for PII,Essentially embedding "customer protection" into the organization's operating mechanism。
2. It’s not “just buy it”:Four key dimensions of PII configuration
- Does the compensation limit match the business scale?:The larger the customer base、The higher the single premium,Limits should generally be more adequate。
- Does the insurance coverage cover major risk scenarios?:Includes advisory advice、File processing、communication error、Employee behavior, etc.。
- Is the deductible designed to be affordable?:Too high a deductible will create real financial pressure when making a claim。
- Are there too many exclusions?:Certain "Looking Cheap" Policies,May exclude key risks。
3. PII and business plans must be linked
If your business plan includes high net worth clients、Cross-regional consulting or complex product distribution,PII terms should be upgraded simultaneously。Supervision will also pay attention to whether the "business risk profile" and "insurance protection configuration" are consistent during review。The two are out of touch,Often you will be asked to provide additional explanations。
Four、In addition to capital and PII,IA actually also looks at these "invisible thresholds"
1. Corporate Governance and Segregation of Duties
Regulators do not want to see a structure where “all decisions are concentrated in one person and there is no review mechanism”。Reasonable organizational structure、Clear reporting path、Checks and balances in key positions,It is an important part of the license review。
2. Internal control and compliance system documents
Common files include but are not limited to:
- Customer due diligence and risk classification process
- Sales suitability and information disclosure mechanism
- Complaint handling and dispute escalation process
- Record keeping system and data confidentiality measures
- Anti-Money Laundering and Counter-Terrorism Financing Policy (AML/CFT)
These files should not be templated,It should be mapped to your real business scenario and team capabilities.。
3. Staff qualifications and ongoing training
Do key personnel have relevant experience?、Do you understand Hong Kong’s local regulatory requirements?、Is there an ongoing training plan?,will affect regulatory confidence。Especially frontline sales and compliance positions,Traceable training and assessment records must be established。
five、Frequent misunderstandings in the application process:Why many companies are “stuck in the middle”
Misunderstanding 1:Treat application as a "form-filling project"
Many application teams focus on formatting and checklists,Ignore "whether the files are logically consistent"。For example, write a business plan with high-end customization,However, PII arrangement and staffing are the basic version.,Supervision will naturally ask questions。
Misunderstanding 2:Only ready for initial submission,No replacement strategy
IA review is often a dynamic communication process。If the patch path is not preset in advance (who is responsible、How long does it take to respond、How to unify caliber),The replacement cycle will be extended indefinitely。
Misunderstanding 3:Separation of capital and operating budgets
Meeting the standard capital is just the starting point。If there is no compliance system、external consultant、Personnel training、Audit and annual review costs are included in the budget,In the early stages of business operations, financial constraints are likely to occur,Impact on subsequent license plate maintenance。
Misunderstanding 4:Ignore subsequent regulatory obligations
Approval of the license does not mean the end。Continuous reporting、System update、Personnel change report、PII renewal and optimization,All are long-term responsibilities。ignore this part,It will discount the initial investment and even trigger regulatory risks.。
six、From "getting the card" to "stabilizing the card":Practical Framework for Annual Review and Continuous Compliance
It is recommended that enterprises establish a two-tier mechanism of "quarterly compliance inspection + annual comprehensive review":
- quarterly inspection:Sample customer files、Sales recording (if applicable)、Disclosure document integrity、Complaint handling time limit。
- Annual review:PII insurance amount and terms evaluation、Capital structure and cash flow health、System update and training effectiveness。
- Event triggered review:When there are high-value complaints、Business model adjustment、When key personnel change,Initiate special compliance review。
This mechanism can significantly reduce the pressure of passive replenishment during the annual review stage.,It is also more conducive to sound management during the business expansion period.。
seven、How to improve your application success rate:Four suggestions for business management
- Build the framework first and then write the material:Determine the business model first、risk map、Organizational Responsibilities,Then output the document。
- “Translate” regulatory language into management actions:For example, converting AML requirements into customer ratings、Suspicious transaction identification、Upgrade reporting process。
- Do stress testing in advance:Simulated complaint、claim、Scenarios such as personnel resignation,Check whether the system is enforceable。
- Introducing a compliance team with practical experience:Reduce trial and error costs,Improve communication efficiency and material quality。
In the field of financial compliance services in Hong Kong,Teams like 88MSO and the 88MSO behind it have been deeply involved in licensing practices for a long time.,The value is often reflected in “translating regulatory requirements into implementable processes”,rather than just assisting in submitting documents。For companies that want to balance efficiency and robust compliance at the same time,This kind of one-stop custody idea makes it easier to overcome regulatory uncertainty。
eight、Conclusion:500,000 capital and PII is the starting point,Compliance operation capabilities are the moat
Back to the topic of this article,500,000 capitalandProfessional Indemnity Insurance PIIindeedHong Kong Insurance Broker LicenseKey thresholds for application,But what really determines whether you can operate in the long term、Can we expand our business safely?,It is a complete set of governance and risk control systems that can withstand regulatory inspections.。
If you are planning to enter the Hong Kong insurance brokerage market,It is recommended to plan from a full-cycle perspective of "getting cards + stabilizing cards":Complete architectural design before applying,Maintain material consistency and response speed during application,Adhere to continuous compliance and dynamic optimization after approval。so,What you get is not just the license itself,Rather, it is a financial business infrastructure for sustainable growth.。
Frequently Asked Questions (FAQ)
Q1:Does it meet the requirements as long as there is HKD 500,000 in the company account?
Not exactly。Supervision usually comprehensively assesses the source of funds、Going concern ability、Budget rationality and business matching。A single "balance meets the standard" is not enough to represent full compliance。
Q2:Can PII be purchased with the minimum configuration first?,Adjustments later?
In theory, it can be adjusted according to business changes,However, if the initial configuration obviously does not match the business plan,,May affect the perception of approval and subsequent risk control。It is recommended to configure according to the actual risk profile from the beginning。
Q3:How long does the application cycle usually take?
Depending on the material integrity、Business complexity depends on the efficiency of replacement parts communication。well prepared、Projects with a clear structure are usually more controllable;on the contrary,The round trip of repair parts will significantly lengthen the cycle。
Q4:What is the most easily overlooked risk after taking a card?
The most common is "business-heavy"、"Light maintenance":Failure to update the system in a timely manner、Training becomes a mere formality、PII insurance renewal without review of terms、Delay in reporting changes to key positions, etc.。
The conditions for obtaining a license must include a record of continued operations.
Hong Kong Insurance Broker License (IA)The application threshold is not just a one-time application issue。The company should assign the responsibilities of the person in charge and business representatives、Customer needs analysis、product comparison、Commission or Interest Disclosure、Customer payment processing、Complaints and file saving are written into executable processes,and leave training、Spot checks and rectification records。
Financial aspects should continuously check capital and net assets、professional indemnity insurance、Separate Client Accounts and Bookkeeping Requirements。When comparing insurance brokerage and insurance agency models,The focus should be on who is represented、What products are available?、How to assume ethical responsibilities and how customer payments are handled,Rather than just comparing license plate names。
Industry references:Hong Kong Insurance Authority:Supervision Code for Licensed Insurance Brokers。