简体中文
 繁體中文
 English

Hong Kong Limited Partnership Fund (LPF) Regime vs Cayman ELP Fund Structure:How to choose offshore funds?
past few years,A clear change is taking place in the Asian asset management market:More and more fund sponsors no longer “choose Cayman by default”,But carefully evaluate the Hong Kong Limited Partnership Fund (LPF) system。Especially the internationalization of the RMB、Growing demand for cross-border family offices、and the trend of regulatory transparency,"Whether the fund structure matches the fundraising objects and strategies?",It has become a factor that determines whether a fund can successfully raise funds.、Smooth operation、Key variables for compliance exit。
Official verification:The regulatory scope covered by this article、Application Information and Ongoing Obligations,should beCayman Islands Monetary Authority investment fund regulatory informationThe current published information shall prevail。
in practice,Many managers will ask:Is the Hong Kong LPF a substitute for the Cayman ELP? Or do they just serve different scenarios? The answer is:The two are not simple substitutes,Instead, each has its own adaptation logic.。This article will start from the legal system、regulatory intensity、tax arrangements、Fundraising preferences、Banking and Auditing Practice、cost effectiveness、Exit mechanism and other core dimensions,System comparisonHong Kong LPF and Cayman ELP,Helping you with “Compliance、efficiency、to make a better solution between "international acceptability"。
one、Let’s look at the conclusion first:LPF and ELP are not "who is better",But "who is more suitable"
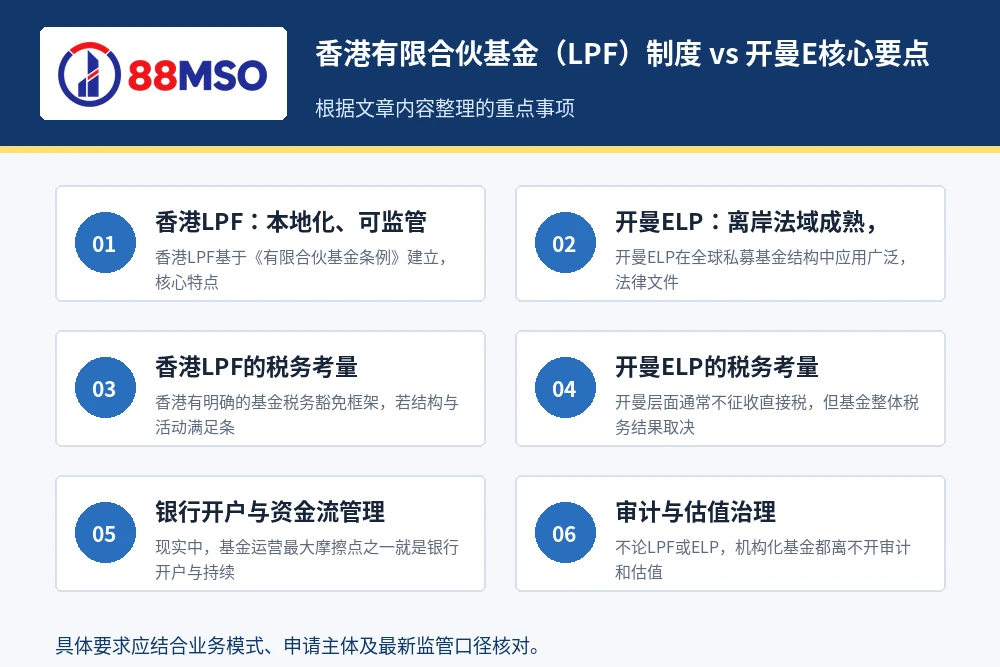
If you sum it up in one sentence:
- Hong KongLPF:More suitable for those who want to strengthen local operations in Asia、Emphasis on regulatory visibility、Managers who value bank account opening and ongoing compliance coordination。
- Cayman ELP:More suitable for traditional USD fund path、A manager for international institutional LPs that uses a mature offshore legal document system。
therefore,The choice shouldn’t just be based on “is it cheap to set up?”,Instead, it should focus on the following questions:
- Where do your investors mainly come from? (Mainland China、Hongkong、Southeast Asia、European and American institutions)
- What is the fund strategy? (VC/PE、secondary market、special opportunity、real estate)
- Is there a need for in-depth linkage with Hong Kong’s licensing system or local compliance team?
- What are the jurisdictional preferences of investors and auditors?
- The future exit is IPO、mergers and acquisitions、distribute,Or structural reorganization?
two、Comparison of institutional foundations:The legal framework is different from the regulatory logic
1) Hong Kong LPF:localization、Regulatory、Emphasis on economic substance
Hong Kong LPF was established based on the Limited Partnership Fund Ordinance,The core features are:Complete registration in Hong Kong、Submission of documents by local attorney、designationinvestment managerandAnti-money laundering manager,and subject to Hong Kong’s anti-money laundering system。It is not a "licensed product" under the regulatory framework of public funds,But in anti-money laundering、record keeping、Clear requirements for operational transparency。
For managers,The advantage of LPF is that:
- and Hong Kong’s local service ecosystem (banks、audit、lawyer、secretary、tax) smooth connection;
- Striking a balance between "visible regulation" and "commercial flexibility";
- Suitable for Hong Kong asset management business、Collaborative construction of family-office structure。
2) Cayman ELP:Offshore jurisdiction matures,Deep understanding of international institutions
Cayman ELP is widely used in global private equity fund structures,Mature legal document templates,International LPs (especially US dollar institutions) understand that the cost is low。For cross-regional fundraising teams,ELP "market education costs" are often lower,Many fund administrations、legal advisor、Audit institutions also have standardized processes。
But at the same time,ELPs generally need to handle more complex cross-border collaborations,Including management of overseas service providers、KYC material penetration、Coordinate with investors for tax disclosure, etc.,In practice, the team’s organizational capabilities are required to be higher。
three、Fundraising Perspective:Investor preferences are diverging
In the past, “Cayman priority” largely came from the traditional preference of US dollar LPs,But now there are three new types of changes:
- Asian Family Offices and High Net Worth InvestorsPay more attention to continuous communication efficiency、Information transparency and regional regulatory predictability;
- Mainland related fundsPay more attention to the connection with Hong Kong’s ecology,including banks、Audit and legal enforcement facilitation;
- International agency LPStill very receptive to Cayman ELP,Especially in the global configuration, the mature path is preferred.。
this means,If your fund-raising targets are mainly Asian capital,Hong Kong LPF usually has more narrative advantage;If the core LP is a European or American institution and has an established legal template,Cayman ELP could be more efficient。Fundraising target portrait,Often more important than "legal reputation"。
Four、Tax and Compliance:Don’t just look at the “nominal tax rate”
1) Tax considerations for Hong Kong LPF
Hong Kong has a clear tax exemption framework for funds,If the structure and activities meet the conditions,Effective tax arrangements can be achieved。But the practical focus is not on “slogan-style tax exemption”,But lies in:
- Whether investment activities fall within the scope of the exemption;
- Whether the management and decision-making functions have reasonable substance;
- management fee、Performance compensation、Whether related transactions leave sufficient traces;
- Does it conflict with the rules of the investor’s tax residence?。
2) Tax considerations for Cayman ELP
There are generally no direct taxes levied at the Cayman level,However, the overall tax consequences of the fund depend on the location of the underlying assets.、Investor tax status、Anti-avoidance rules (such as substantive、information exchange、controlled foreign company rules, etc.)。Many GP misunderstandings are “Cayman = automatic tax benefits”,In fact, tax results are still the product of multi-jurisdictional linkage.。
therefore,Whether you choose LPF or ELP,It is recommended to complete a version before setting up“Investor Tax Impact Map”,Avoid tax disputes during later distribution。
five、Operational practice:Open an account、audit、Documentation and ongoing maintenance
1) Bank account opening and capital flow management
in reality,One of the biggest friction points in fund operations is bank account opening and ongoing transaction review。When communicating with local banks, Hong Kong LPF,Usually in the file path、Check the logic、Actual control explanations are more predictable;ELP is not impossible to open,However, more adequate cross-border explanations and supplementary procedures are often required.。
For managers who emphasize capital efficiency,It is recommended to synchronize the design from the early stage of establishment:
- Fund level and SPV level account matrix;
- Investment money、management fee、Distribution path and voucher logic;
- KYC update rhythm and investor information management mechanism。
2) Audit and valuation governance
Regardless of LPF or ELP,Institutional funds are inseparable from auditing and valuation governance。The difference is not just about "who will judge",What's more:
- Can audit papers cover cross-border SPVs?;
- Whether the valuation policy is written into the LPA and side letter in advance;
- Are major valuation adjustments supported by investment committee records?。
If these basic governance are done well,Second stage of subsequent fundraising、It will be much smoother for old LPs to continue investing。
six、Cost and timeliness:Don’t just count the establishment fee,Calculate "full cycle costs"
Many teams compare LPF and ELP,Just look at the registration cost。But what really affects IRR is the full cycle cost,include:
- Establishment stage:law、register、secretary、Due diligence document organization;
- Operational stage:audit、Administration、Compliance declaration、bank maintenance;
- change stage:GP changes、Strategy adjustment、Additional recruitment、Parallel Fund;
- exit phase:Assign execution、tax review、Liquidation and cancellation。
Generally speaking,If the core operation of the team is in Hong Kong、And asset activities are deeply bound to Hong Kong’s service ecosystem.,The overall synergy efficiency of LPF may be higher;If the team already has a mature Cayman service provider network and global institutional LP foundation,ELP may still have scale efficiencies。
seven、Governance structure and risk isolation:LPA design determines “risk resistance”
Whether you choose LPF or ELP,What really determines the long-term stability of the fund,is a partnership agreement (LPA) and supporting governance documents。Key suggestions to pay attention to:
- GP authority boundaries:Related party transactions、loan、Valuation caliber、Voting mechanism for major matters;
- LP protection clause:key person clause、Removal without fault、right to information、fee cap;
- conflict management mechanism:Parallel Fund、Opportunity allocation、Follow-up investment rules;
- Exit and liquidation paths:Distribution in kind、extension clause、Dispute Resolution Jurisdiction。
Practical experience shows:same jurisdiction,The risk gap between high-quality documents and weak documents,Far larger than the difference between "LPF or ELP"。
eight、Which scenarios are more suitable for Hong Kong LPF? Which ones are more suitable for Cayman ELP?
More suitable for typical scenarios of Hong Kong LPF
- Target LP is based in Hong Kong、Mainland-based family offices and regional capital;
- Hope and Hong Kong Asset Management、banking system、The audit system forms a closed loop;
- Emphasis on explainability of anti-money laundering and operational compliance,Improve long-term financing credit;
- Hong Kong local licenses and financial business synergy may be expanded in the future。
Typical scenarios more suitable for Cayman ELP
- The target LP is European and American institutions、FOF、Mainly international capital such as pension funds;
- There are already mature USD fund templates and overseas service provider collaboration frameworks;
- Fund strategies are highly internationalized,Investment targets cover multiple jurisdictions;
- LP side has high acceptance of Cayman Act documents,Due diligence path standardization。
Nine、Dual architecture idea:Not an alternative
In the practice of some medium and large managers,Will adopt "dual architecture" or "master-slave structure":For example, focusing on a certain jurisdiction as the main fund,Another jurisdiction as a parallel vehicle,Undertake LP from different sources respectively。This can take into account both international LP habits and Asian LP preferences.,But for legal affairs、tax、Higher requirements for consistency in information disclosure。
If dual architecture is adopted,Be sure to unify in advance:
- cost sharing principle;
- opportunity allocation algorithm;
- Valuation policy consistency;
- Disclosure standards and reporting rhythm。
ten、Practical suggestions:Use the "5-step decision-making method" to quickly implement
- first step:Lock in investor portraits——First determine the top 10 potential LP types,Then infer the legal domain。
- Step 2:Drawing tax penetration diagrams——At least covering the fund level、SPV layer、Asset layer、investor level。
- Step 3:Verify the feasibility of opening an account——Pre-communicate the KYC path with the target bank before establishment。
- Step 4:Establish a compliance operation mechanism——Put AML、Data retention、Audit cooperation is written into the daily process。
- Step 5:Default opt-out and dispute mechanism——Write clearly what to do in bad times in good times。
For teams looking to build long-term financial compliance capabilities in Hong Kong,It is recommended to introduce familiar license plates、Consulting team linking anti-money laundering and cross-border structures。Take 88MSO and the 88MSO practice system behind it as an example,Its advantages are not limited to “applying for a certain license”,It lies in the structure of the fund、Compliance mechanism、Bank coordination and follow-up regulatory communication are opened up,Reduce manager’s later operational friction。
Conclusion:Offshore fund structure selection,The essence is "strategic matching" rather than "template copying"
Neither Hong Kong LPF nor Cayman ELP is a panacea answer。A really solid choice,Depends on your fundraising map、Asset strategy、Team Capabilities and Compliance Objectives。Offshore fund competition today,It has moved from “who builds the structure first” to “who can continue to comply with regulations”、Stable delivery”。
If you are in the fund launch stage,The most worthwhile investment is not "where is cheaper",Instead, get the structural logic right first.:Investors can understand、bank can accept、Audit can be implemented、Regulation can explain、Exit can be executed。When these five points are established at the same time,Architecture truly serves performance。
FAQ:The 4 most common questions managers ask
Q1:Will the LPF completely replace the Cayman ELP?
Won't。The two serve different objects。LPF has obvious advantages in local synergy in Asia,ELP remains strong in international institutional recognition,It is more likely to coexist for a long time in the future。
Q2:Is it necessarily easier to raise funds if you choose LPF?
uncertain。The core of fundraising is strategy、Performance and team credibility。LPF can improve the acceptance of some LPs,But it cannot replace fund fundamentals。
Q3:Is the Cayman ELP “lighter” in terms of compliance?
It is not recommended to understand it this way。Cross-border information exchange、KYC、Audit and tax penetration requirements are increasing,Compliance pressure is just distributed in different links。
Q4:Establishing a fund for the first time,What should be done first?
First, conduct a feasibility assessment of the trinity of "investor + tax + account opening",Then decide the jurisdiction。This can avoid the high cost of changing the architecture later.。
Structural selection goes back to investors and assets themselves
When comparing Hong Kong Limited Partnership Fund (LPF) regime vs Cayman ELP fund structure,The number and location of investors should be confirmed first、Subscription and redemption arrangements、Asset type、Manager's location、Tax filing and exit methods。LPF、ELP、VCCs or trusts each solve different problems,It cannot be decided solely by the speed of establishment or the initial cost.。
The landing documents must clearly assign general partners、investment manager、director、trustee、Administrator、Responsibilities of Trustees and Auditors,and process valuations in advance、conflict of interest、Related party transactions、Cost Sharing and Investor Reporting。When it comes to investment immigration or family inheritance,Eligibility rules and benefit arrangements should also be independently checked。
Industry references:Hong Kong Companies Registry:limited partnership fund system。
Read more:Analysis of key points of Singapore VCC architecture:Why are high-net-worth families around the world competing to set up?、Singapore RFMC (registered fund management company) license application conditions and AUM threshold。