简体中文
 繁體中文
 English

Hong Kong MSO licensed company bank account opening,Why do I always get stuck at the "last level"?
Already got manyHong Kong MSO License(Money Service Operator,Money Service Operator License) for enterprises,The most critical step before actually starting a business,Often it’s not the card itself,RatherSuccessfully open and use a bank account stably。No account,It will be difficult to complete the collection of funds、Cross-border payment、Customer settlement and daily operations;Account opening is slow、Quota limited、Low compliance score,It will also directly affect the business growth rate。
in reality,Many applicants will be similarly confused:The company materials are clearly complete,Why do banks keep making replacements? Why did I feel like I had a good answer on the day of the interview?,But still rejected? The core reason is that:Banks’ review of the MSO industry does not just look at “the presence or absence of documents”,See moreIs the risk identification logic closed loop?,i.e. "who are you、do what、with whom to do、where does the money come from、where to flow、How to continue to control”。
This article will take a practical perspective,System dismantling of the critical path for account opening for Hong Kong MSO licensed companies:Compliance Materials List、KYC Q&A Framework、Interview communication skills、Common rejection minefields and post-account maintenance strategies。If you want to pass the due diligence stage in one go,Reduce back-and-forth repairs,This content serves as a complete implementation checklist。
one、First understand the underlying logic of bank review:Not "approval",But "risk pricing"
The bank does not simply judge “can open/can’t open”,It's about assessing whether you're willing to take on your business risk,And what kind of risk control conditions should be used to undertake it?。to MSO companies,Banks mainly focus on four dimensions:
- Licensing and regulatory status:MSO license validity、Whether the business scope matches actual transactions。
- Business model transparency:source of income、Capital flow path、Is the counterparty type clear and verifiable?。
- AML/KYC internal control capabilities:Customer due diligence、Suspicious transaction monitoring、Are high-risk national screening mechanisms enforceable?。
- Management Compliance Maturity:director、shareholder、Can the person in charge of compliance give consistent answers during the interview?、major、A practical answer。
in other words,What banks look at is “whether you can operate in compliance with regulations in the long term.”,rather than "How many documents did you prepare today?"。This is why many companies have complete materials but still encounter obstacles - the files are static,What banks need to look at is dynamic control capabilities。
two、"Pre-review preparation" before opening an account:Determines 80% of success rate
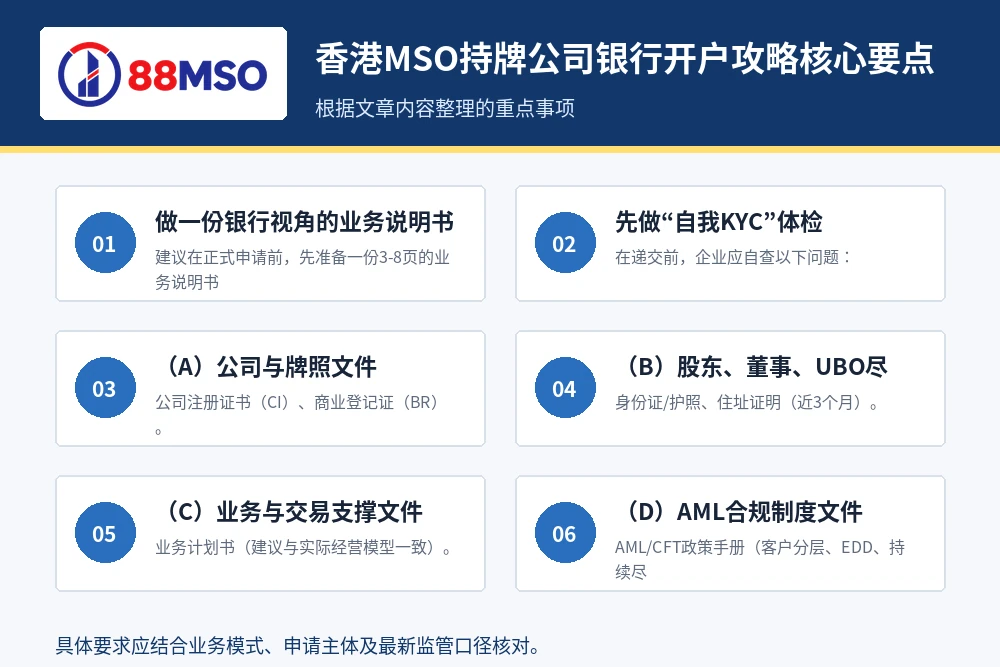
1. Make a business narrative from a bank perspective (Business Narrative)
It is recommended that before formal application,First prepare a 3-8 page business description,Use "non-marketing language" to explain the whole business clearly,Highlights include:
- Target customer portrait (individual/business、Geographical distribution、Industry attributes)。
- Core service types (exchange、money transfer、Acquiring、Wallet liquidation, etc.)。
- Typical trading path (deposit、transit、Withdrawal node)。
- Estimated monthly trading volume、Single range、peak scenario。
- Risk control mechanisms (sanction screening、Transaction monitoring、Manual review threshold)。
The purpose of this document is:Let bank account managers and compliance teams quickly form a common understanding,Avoid repeated patching due to information fragmentation。
2. Do a “self-KYC” physical examination first
before submission,Enterprises should self-examine the following issues:
- Is shareholder penetration complete?,Is the ultimate beneficiary (UBO) traceable?
- Are there any historical transactions or affiliations involving high-risk jurisdictions?
- Have directors/management disclosed any negative information?、Records of litigation or regulatory penalties?
- Official website、contract、bill、Is the business description consistent?
Many rejections are not because the company has "problems",It is because of "inconsistent information" that triggers a secondary review。Get a physical exam in advance,can significantly reduce this risk。
three、List of compliance materials for bank account opening of Hong Kong MSO licensed companies (practical version)
The versions of different banks are slightly different,However, the following materials are basically necessary for high frequency:
(A) Company and license documents
- Certificate of Incorporation (CI)、Business Registration Certificate (BR)。
- Constitutional documents (M&;A) and the latest annual return documents。
- Hong Kong MSO license certification document (including validity period、license number)。
- Proof of office address (lease/utility bill/serviced office contract)。
- Organizational chart (including equity ratio、control relationship)。
(B) Shareholders、director、UBO due diligence documents
- ID card/passport、Proof of address (last 3 months)。
- Personal resume (financial、pay、Compliance related experience is a plus)。
- Statement of source of funds and wealth (SOF/SOW)。
- Tax residency document (if required)。
(C) Business and transaction supporting documents
- Business plan (recommendations consistent with actual business model)。
- Major customer/supplier contract sample or letter of intent for cooperation。
- Estimated trading volume report by currency、area、Product dimension split)。
- Fund flow diagram (complete closed loop from client to settlement)。
- Official website、System screenshot、Product process description。
(D) AML compliance system documents
- AML/CFT Policy Manual (Customer Stratification、EDD、Continuous due diligence)。
- KYC account opening process and risk rating model。
- Sanctions and PEP Screening Mechanism Description。
- Suspicious Transaction Report (STR) Internal Reporting Process。
- Employee Compliance Training Records and Compliance Officer Responsibilities Description。
Practical reminder:“Available” materials does not mean “available”。Banks pay more attention to whether documents corroborate each other:For example, the target market in the business plan,Required and contract sample、Website language version、Expected transaction currency to match。
Four、The interview is a "compliance defense":The three types of people must have the same caliber
MSO account interviews usually involve directors、actual controller、Head of Operations or Head of Compliance。The most common question is not "can't answer",But "everyone speaks his own words"。It is recommended to conduct an internal rehearsal before the interview,Ensure that the following three categories of calibers are unified:
- commercial caliber:What money does the company make?、who is the customer、Why you need this bank account。
- Compliance caliber:How to identify high-risk customers、How to deal with abnormal transactions。
- Operational caliber:Transaction frequency、Payment country、Currency structure、Refund and dispute handling mechanism。
High-frequency interview questions and answer framework
Question 1:Where do your customers mainly come from?
Answer suggestions:Split proportionally (e.g. region、industry),And explain the proportion control measures in high-risk areas。
Question 2:How to confirm that the source of funds is legal?
Answer suggestions:Describe the dual mechanism of KYC + transaction monitoring,An example of the manual review process after triggering the threshold。
Question 3:How much is the expected monthly turnover? Why?
Answer suggestions:Gives three forecasts of "conservative-baseline-expansion",And correspond to contract reserves or historical data。
Question 4:What should I do if a customer hits the sanctions list?
Answer suggestions:Freeze/Reject Transaction Immediately、Upgrade compliance audit、Internal records and necessary regulatory reporting paths。
Question 5:Why choose Hong Kong as your business hub?
Answer suggestions:Regulatory transparency、Robust legal system、Improved cross-border financial infrastructure,And combined with the company's strategy rather than vague statements。
The answer principle can be summarized as:specific、Verifiable、Executable。Avoid empty words such as “We will strictly comply with regulations”,Use process as much as possible、threshold、express job responsibilities。
five、8 minefields that are most likely to lead to denial or delay
- Minefield 1:Business description is too broad,Such as “doing global remittances”,Lack of boundaries and scenes。
- Minefield 2:Trading volume forecasts are significantly distorted,and team size、Customer reserve mismatch。
- Minefield 3:The shareholder structure is complex but lacks penetrating documents,UBO is not clear。
- Minefield 4:The official website is inconsistent with the application materials (product、area、Currency description conflict)。
- Minefield 5:The AML system is heavily templated,Can't explain how it's actually implemented。
- Minefield 6:Interview personnel are not familiar with the front-line process,Can only memorize written materials。
- Minefield 7:Abnormal transactions occurred in historical related companies,No explanation and isolation in advance。
- Minefield 8:Ignore ongoing due diligence after account opening,Resulting in being banned or censored in the short term。
six、It really starts after opening an account:Key points of account maintenance and compliance operations
Many companies regard "successful account opening" as the end point,In fact, what banks are most concerned about is the behavioral data after opening an account.。It is recommended to establish the following mechanism:
1. Trading behavior should be consistent with reporting standards
The currency promised when opening an account、nation、customer group,Should be basically consistent with the actual transaction。If there is a new country/large amount exception,Business changes need to be explained to the bank in advance。
2. Regularly update KYC and company documents
Change of directors、Equity adjustment、Address migration、Business upgrades and other matters should be notified to the bank in a timely manner。Delayed updates are a frequent cause of censorship。
3. Establish an internal “audit trace” mechanism
Perform customer due diligence、List screening、Disposal of suspicious transactions、Compliance training and other key nodes leave traces,Facilitate quick response to bank spot checks or regulatory inquiries。
4. Annual review and license maintenance are synchronized
MSO license maintenance、Audit report、tax declaration、It is best to schedule bank due diligence updates uniformly,Avoid "document time misalignment" causing a decrease in compliance impression。
seven、How to improve account opening efficiency:What is the value of professional advisors?
For companies that are deploying financial business in Hong Kong for the first time,The difficulty in opening an account is often not in a single file,And in the conversion of "regulatory language" and "banking language"。Experienced compliance teams often achieve significant improvements in:
- According to different bank preferences,Customized material structure and narrative focus。
- Identify high-risk points in advance,Design reinforcements rather than passive fixes。
- Organize interview rehearsals,unified director、operations、Compliance person in charge。
- Maintain SOP after establishing account opening,Lower limit、freeze、Risk of closing the account。
Take an organization that has long been involved in Hong Kong licensing and compliance services as an example (such as the one-stop service model represented by 88MSO/88MSO),The advantage usually lies in applying for a license、Bank account opening、AML landing、Subsequent annual review and maintenance will be cleared,Help enterprises reduce cross-link information gaps。This “whole case perspective” is especially critical for MSO companies。
Conclusion:Treat account opening as the first "stress test" of compliance management capabilities
Hong Kong MSO licensed company bank account opening,It’s never a simple administrative action,It’s about the bank’s ability to comply with corporate compliance、The first systematic assessment of business transparency and management levels。The sooner you prepare、The more consistent the material is、The interview becomes more professional,The higher the success rate,The stability of subsequent accounts will also be stronger。
If you are in the process of opening an account,It is recommended to implement them one by one according to the list in this article.:Build a business narrative first,Further improve the KYC/AML evidence chain,Finally, unified caliber through interview drill。Turn "passive supplements" into "active certifications",You will clearly feel the improvement in audit communication efficiency。
FAQ:Frequently Asked Questions about Hong Kong MSO Account Opening
Q1:How long after obtaining the MSO license can I apply to open a bank account?
In theory, you can apply immediately,However, it is recommended to complete the business description first、AML system and contract sample preparation,It is safer to submit again。
Q2:Do I have to go to Hong Kong in person for the visa interview?
Depends on bank policy。Some banks support video or witness mode,However, the MSO industry usually prefers on-site signing,higher success rate。
Q3:Can a new company with no historical records open an account?
Can,But need to provide a more convincing business plan、Customer source certification and transaction prediction logic。
Q4:How long does it take to apply again after being rejected for account opening?
no unified standard。It is recommended to review the rejection reasons first,Reinforce high-risk points before changing banks or resubmitting,Avoid short-term repeated failures leaving bad records。
First determine whether the business falls within the scope of MSO based on capital flow.
When evaluating Hong Kong MSO licensed company bank account opening,What should be handed over from the customer to the company?、How the company exchanges or remits、Which accounts do the funds go through?、What assets are finally delivered to start drawing the capital flow?。Just looking at the product name is not enough to determine the scope of regulation;Involving legal currency exchange、Cross-border remittance、When collecting and paying virtual assets or third parties,It is also necessary to check separately whether other regulatory systems are applicable at the same time.。
Application and going concern information should cover actual business location、Equity and ultimate owners、fit and proper person、business plan、risk assessment、Customer due diligence、Sanctions Screening、Transaction monitoring、Report suspicious transactions、Record keeping and staff training。During on-site inspection,Institutional documents、Sampled customer files and bank statements must be mutually corroborative。
Industry references:Hong Kong Customs and Excise Department:Money service operator supervision and licensing information。